The High-Stakes Geopolitics of Rare-Earth Minerals: Why China Will Maintain the Embargo Specter While the West Chases Elusive Self-Sufficiency

Global economic security has rapidly transitioned from a theoretical academic discussion into the paramount strategic priority for governments worldwide. As supply chain vulnerabilities become increasingly weaponized in an era of heightened geopolitical competition, the architecture of international trade is undergoing a profound structural shift. Nowhere is this dynamic more apparent than in the critical minerals sector, where the asymmetrical relationship between China and Western economies defines the modern contours of industrial policy and national security. While Beijing likely refrains from executing a total embargo on rare-earth elements, it maintains the persistent threat of one as a potent diplomatic and economic lever. Simultaneously, major Western powers pursue aggressive policies to insulate their industrial bases from potential shocks, even as true self-sufficiency remains an exceptionally difficult, if not practically impossible, target to achieve.
The current landscape is characterized by a delicate, high-stakes standoff. On one side, the world’s largest economies, spearheaded by the United States and the European Union, are deploying massive legislative and financial interventions to restructure global supply chains. These measures range from stringent regulatory frameworks and trade incentives designed to force economic partners to alter compliance behaviors to substantial subsidies aimed at reshoring processing capabilities. For smaller economies caught in the crossfire of this great power competition, the pathways to economic security are narrower and more pragmatic. Lacking the fiscal fire-power to build fully domestic alternative supply chains, smaller nations rely almost exclusively on strategic diversification to mitigate the risks of geopolitical coercion and market bullying.
Main Facts and the Structural Realities of Rare-Earth Dominance
Rare-earth elements—a group of 17 chemically similar metallic elements that include neodymium, dysprosium, and praseodymium—are the foundational building blocks of the twenty-first-century green and digital economies. They are indispensable for the manufacturing of permanent magnets used in electric vehicle (EV) motors, wind turbine generators, advanced defense systems, guidance controls, and consumer electronics. Without secure access to these materials, the ambitious decarbonization and technological modernization goals of the West face immediate, insurmountable bottlenecks.
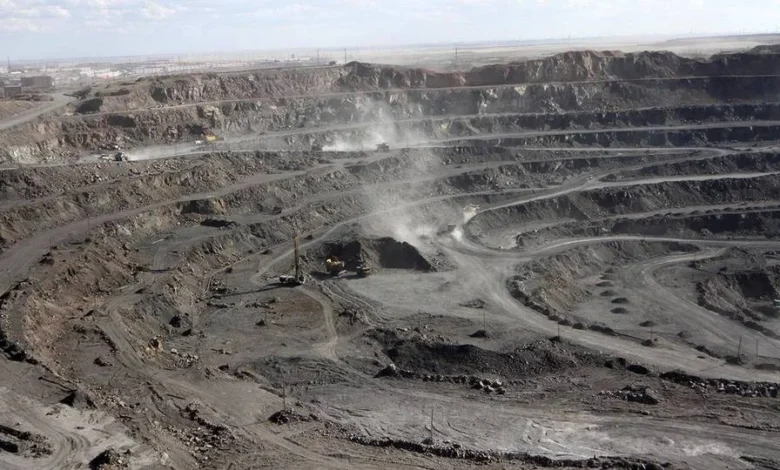
China’s current dominance in this sector is not merely a product of natural resource endowment, but the result of a decades-long industrial strategy. According to data compiled by the International Energy Agency (IEA) and the United States Geological Survey (USGS), China accounts for roughly 60 percent of global rare-earth mining production. However, its true monopoly power lies further down the value chain. China controls approximately 70 percent of global rare-earth processing and an astonishing 90 percent of the world’s production of advanced rare-earth permanent magnets.
This absolute stranglehold on midstream refining and downstream manufacturing creates a profound structural vulnerability for Western democracies. Even when rare-earth ores are mined in countries like the United States, Australia, or Greenland, a vast majority of those materials have historically been shipped to China for the environmentally hazardous and technologically complex processes of separation and refinement. Breaking this cycle requires massive capital expenditure, long lead times, and significant environmental trade-offs that Western regulatory frameworks often struggle to accommodate.
Chronology of Escalation: From Market Shock to Strategic Awakening
The realization of rare-earth vulnerability did not happen overnight; it is the culmination of a multi-decade evolution in global manufacturing and geopolitical friction.
The first major wake-up call occurred in 2010 during a diplomatic dispute between China and Japan over a collision involving a Chinese fishing trawler near the disputed Senkaku/Diaoyu Islands in the East China Sea. In response to the detention of the trawler captain, Beijing informally halted rare-earth shipments to Japan. Although Beijing officially denied implementing an embargo, the disruption caused global prices to spike exponentially—in some cases by several hundred percent—and forced Japanese industries to scramble for alternative suppliers and recycling technologies. This 2010 incident served as the foundational case study for the weaponization of trade in critical raw materials.
Throughout the 2010s, as global demand for smartphones, wind turbines, and hybrid vehicles surged, Western policymakers largely remained complacent, lulled by the assumptions of a frictionless globalized marketplace. However, the subsequent intensification of US-China trade tensions in 2018 and 2019 brought the issue back to the forefront of geopolitical strategy.
The COVID-19 pandemic further exposed the fragility of deeply integrated, single-source supply chains. By 2021 and 2022, both Washington and Brussels began drafting comprehensive industrial strategies. The passage of the US Inflation Reduction Act (IRA) in 2022 and the European Union’s proposed Critical Raw Materials Act in 2023 marked a definitive turning point. These legislative packages established concrete benchmarks: by 2030, the EU aims to extract 10 percent, process 40 percent, and recycle 25 percent of its strategic raw materials domestically, while ensuring that no single third country provides more than 65 percent of any strategic raw material at any stage of processing.
In response to Western containment strategies and semiconductor export controls, Beijing began tightening its own regulatory grip on critical minerals. In mid-2023, China’s Ministry of Commerce announced export controls on gallium and germanium—metals critical to semiconductor manufacturing—followed closely by restrictions on graphite and specific rare-earth processing technologies in late 2023 and 2024. These actions demonstrated Beijing’s willingness to use administrative controls without resorting to a total, catastrophic embargo that would severely damage its own export-driven industrial economy.
Supporting Data and Economic Realities
The economic dimensions of decoupling or de-risking from China in the rare-earth sector are monumental. Financial analysts and commodity market experts estimate that replacing Chinese processing capacity requires tens of billions of dollars in direct capital investment over the next decade.
Consider the timeline for developing a rare-earth mine and processing facility: from initial geological discovery to commercial production, the timeline typically spans 10 to 15 years. This protracted development cycle clashes directly with the urgent timelines established by Western governments for achieving net-zero carbon emissions by 2050.
Furthermore, data from the Center for Strategic and International Studies (CSIS) highlights the extreme concentration of intellectual property and engineering expertise. China holds the vast majority of patents related to rare-earth extraction, separation chemistry, and magnet manufacturing. Western mining companies attempting to replicate these processes face steep technological learning curves, often resulting in cost overruns and operational delays.
To mitigate these risks without achieving total self-sufficiency, Western nations are pursuing a dual-track strategy of capacity duplication and strategic stockpiling. The United States Department of Defense has injected hundreds of millions of dollars into domestic processing facilities, such as the MP Materials facility in Mountain Pass, California, and various nascent rare-earth separation projects in Texas and Australia. Simultaneously, strategic reserve initiatives are being bolstered to buffer against short-term supply shocks, acknowledging that complete autarky is economically inefficient and practically unattainable.
Official Responses and Strategic Postures
Governments and industry leaders across the globe have articulated distinct approaches to managing the rare-earth dilemma, reflecting their unique geopolitical positions.
Washington has maintained a bipartisan consensus on the necessity of decoupling critical mineral supply chains from perceived adversaries. US officials frequently emphasize that economic security is national security. The Department of Commerce and the Department of Energy have collaborated closely with allies through frameworks like the Minerals Security Partnership (MSP) to pool resources, finance alternative mining projects in developing nations, and establish transparent supply chains that bypass Chinese monopolies.
In Brussels, the European Union has adopted a nuanced vocabulary, shifting from the broader concept of "decoupling" to the more pragmatic approach of "de-risking." European Commission leaders have repeatedly stressed that the EU remains open to trade with China but refuses to remain dangerously dependent on a single supplier for the foundational elements of its green transition. European industrial associations, however, have expressed anxiety regarding high energy costs and stringent environmental regulations within the bloc, which can make domestic rare-earth refining significantly more expensive than importing processed materials from Asia.
Beijing, for its part, maintains a consistent official narrative. Chinese authorities contend that their export control measures are standard regulatory practices designed to protect national security, environmental resources, and sustainable development, aligning fully with international trade rules. Chinese trade officials have frequently criticized Western protectionism and industrial subsidies, arguing that artificial attempts to distort global markets will ultimately prove counterproductive and economically burdensome for consumers worldwide.
Broader Impact and Implications for Global Trade
The ongoing dynamics surrounding rare-earth minerals carry profound implications for the future of globalization. The era of pure cost-efficiency as the sole guiding principle for international supply chains has effectively ended. In its place, a new paradigm of "friend-shoring" and "reshoring" is reshaping international commerce, introducing persistent inefficiencies and inflationary pressures into the global economy.
For the West, the strategy of duplicating capacity and building stockpiles serves as an essential insurance policy against geopolitical coercion. However, it comes with a steep price tag. Industrial consumers of rare earths—ranging from automotive giants to defense contractors—must absorb higher component costs, which are ultimately passed down to end-users. This dynamic threatens to slow the pace of global energy transition technologies if input costs remain artificially inflated due to market fragmentation.
For China, maintaining the specter of an embargo without actually pulling the trigger serves as a masterclass in strategic ambiguity. By keeping Western capitals perpetually uncertain about the future availability of critical minerals, Beijing exercises considerable geopolitical leverage, deterring overly aggressive trade measures while preserving its export revenues.
Ultimately, neither side will achieve its maximalist goals. China will likely refrain from a total embargo that would trigger catastrophic retaliation and permanently destroy its reputation as a reliable, albeit assertive, trading partner. Conversely, the West will not achieve complete self-sufficiency due to the immense capital, time, and environmental hurdles involved. Instead, the global economy is settling into a protracted period of managed interdependence, where supply chain resilience, strategic diversification, and continuous risk management define the baseline of international relations.