Unexpected Health Crises Highlight the Critical Need for Long-Term Disability Planning and Financial Resilience

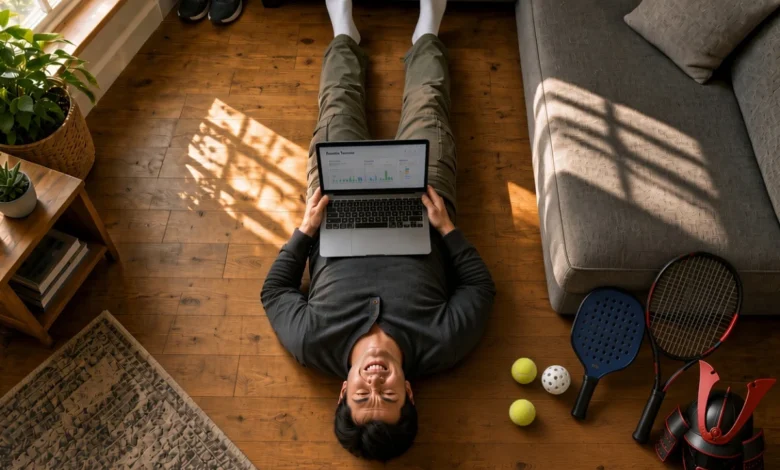
Recent personal health scares experienced by prominent financial commentators and independent professionals have brought renewed attention to a frequently overlooked aspect of personal finance: disability preparedness. While public discourse surrounding financial planning typically focuses on retirement savings, investment portfolios, and life insurance, unexpected health disruptions demonstrate that the loss of earning capacity during one’s working years remains a substantial risk for households dependent on active labor income.
The Chronology of Vulnerability: A Sequence of Physical Setbacks
The discussion surrounding modern financial vulnerability often stems from acute, unexpected physical events that temporarily or permanently impair an individual’s ability to work. In a recent case study highlighting these risks, a series of compounding health episodes over the course of a single year exposed the fragility of active income generation.
The timeline began earlier in the year with a prolonged, two-week respiratory illness complicated by a chronic childhood asthma condition. For individuals managing respiratory sensitivities, acute infections frequently lead to extended recovery periods and diminished physical stamina. This vulnerability was further tested during a routine professional consultation call conducted while the individual was still recovering. Sustained heavy talking for over an hour without adequate, deep breathing resulted in acute physical exhaustion, drawing sharp parallels to the chronic stress-induced fatigue experienced during rigorous corporate finance careers.
Shortly thereafter, a secondary physical crisis occurred when a routine movement triggered acute spinal pain, reminiscent of an injury sustained previously while performing community service activities. This acute back pain was precipitated by a compressed timeframe of intense physical exertion: a high-level pickleball session followed by tennis instruction, intensive weightlifting aimed at progressive loading personal records, and a subsequent hilly morning walk.
This sequence of events underscores how physical overexertion, combined with chronic stress and the natural physiological changes associated with aging, can suddenly compromise mobility. For traditional W-2 employees or self-employed professionals, such incidents immediately threaten the ability to maintain regular business operations, meet client obligations, and secure household income.
Statistical Reality: Understanding Long-Term Disability Risks
Public perception often associates long-term disability with catastrophic accidental injuries, such as severe traffic collisions or falls from elevated heights. However, comprehensive actuarial data reveals a starkly different reality. According to statistics from the Social Security Administration (SSA) and major insurance providers, accidental injuries account for a minority of long-term disability claims, typically ranging between 9% and 12%.
Instead, the vast majority of extended absences from the workforce stem from chronic medical conditions and musculoskeletal disorders. Musculoskeletal issues—including severe back pain, spinal disorders, and joint complications—consistently represent the leading category of long-term disability claims, accounting for roughly 26% to 33% of all cases. Furthermore, actuarial projections indicate that approximately 25% of current 20-year-olds will experience a disabling condition lasting one year or more before reaching standard retirement age.
These figures illustrate that the primary threat to an individual’s earning potential is not a dramatic, high-risk accident, but rather the gradual wear and tear on the human body combined with unexpected illness. Consequently, financial advisors emphasize that disability insurance should not be viewed as an optional luxury for high-risk occupations, but as a fundamental component of comprehensive risk management.
Short-Term Versus Long-Term Coverage: Structural Differences
Navigating disability insurance requires a clear understanding of the distinctions between short-term disability (STD) and long-term disability (LTD) policies. These instruments serve entirely different functions within a financial plan.
Short-term disability insurance is designed to cover temporary medical absences, such as recovery periods following scheduled surgeries, acute injuries, or short-term illnesses. STD policies typically replace between 50% and 70% of an individual’s gross income, with benefit durations ranging from a few weeks up to six months. These plans generally feature a brief elimination period—the waiting period before benefits begin—often lasting between one and two weeks. While some employers provide group STD coverage, and a select number of U.S. states mandate state-run disability programs, self-employed individuals must independently secure private policies to obtain coverage.
In contrast, long-term disability insurance is structured to protect against extended or permanent loss of income. LTD benefits typically initiate after a designated elimination period, commonly 90 days, and replace approximately 60% of pre-disability earnings. Policies may disburse funds for a specified term or continue until the policyholder reaches retirement age.
Industry experts emphasize two critical policy provisions when evaluating LTD coverage:
- Definition of Disability: Policies may define disability based on an "own-occupation" standard—meaning you are considered disabled if you cannot perform the specific duties of your current profession—or an "any-occupation" standard, which requires that you are unable to perform any job suited to your education and experience. Own-occupation riders offer significantly stronger protection for specialized professionals.
- Taxability of Benefits: If premiums are paid using pre-tax employer dollars, the received benefits are generally treated as taxable income. Conversely, if policies are purchased using after-tax personal funds, the benefit payouts are typically tax-free.
Furthermore, reliance on Social Security Disability Insurance (SSDI) as a primary safety net is discouraged by financial planners. SSDI features strict qualification criteria, a mandatory five-month waiting period, and modest average payout amounts, serving primarily as a baseline safety floor rather than a comprehensive replacement strategy.
Strategic Frameworks for Financial Resilience
To mitigate the financial impact of unexpected health disruptions, financial analysts and wealth management professionals recommend a multi-layered defensive strategy.
1. Audit and Enhance Disability Insurance Policies
Workers with employer-sponsored benefits are advised to regularly review their human resources portals to examine group LTD limits, which frequently cap monthly payouts and may leave high-earning individuals underinsured. Supplementing group plans with individual private policies—ideally incorporating an own-occupation rider—ensures continuity of coverage regardless of future employment changes. Self-employed workers must proactively establish individual coverage while young and healthy to avoid exclusions for pre-existing conditions.
2. Establish Robust Emergency Liquidity Reserves
Because disability policies involve mandatory waiting periods—ranging from weeks for short-term plans to months for long-term coverage—households must maintain adequate liquid reserves. Financial planners generally recommend holding a minimum of six to twelve months of essential living expenses in highly liquid, low-risk instruments such as cash equivalents or short-term government securities. This buffer ensures that ongoing financial obligations, including housing costs and debt service, can be met during the transition from active income to disability benefits.
3. Diversify Income Streams Beyond Labor-Intensive Work
Relying on a single source of active income creates a critical vulnerability in the event of health complications. Establishing secondary revenue streams—such as passive investment income, digital content platforms, royalties, or online enterprises—reduces dependence on physical labor. Crucially, experts suggest prioritizing alternative revenue models that do not require physical presence or manual exertion, allowing income generation to continue during periods of limited mobility.
4. Accelerate Savings During Peak Health and Earning Years
Because peak earning years often coincide with peak physical health, financial strategies should account for the possibility of an early or abrupt exit from the workforce. Aggressive saving and investing during early and mid-career stages—including maximizing contributions to tax-advantaged accounts and systematically paying down fixed living expenses—reduce the total income replacement required should a disability occur. Lower fixed overhead directly correlates with enhanced financial security.
5. Prioritize Proactive Health and Legal Risk Management
Finally, treating physical well-being as a primary economic asset is essential for long-term stability. Routine medical evaluations, appropriate recovery periods following physical activity, and stress management play a vital role in preventing chronic injuries. Simultaneously, securing foundational legal protections—including comprehensive term life insurance, valid wills, financial powers of attorney, and healthcare directives—ensures that both medical and financial contingencies are adequately addressed before crises materialize.
Broader Implications for the Modern Workforce
The intersection of physical health and financial stability underscores a broader economic reality: human capital is the foundational asset upon which all personal wealth is built. As workplace structures evolve and independent contracting grows, the responsibility for risk management increasingly shifts from corporate institutions to individual workers.
By recognizing the statistical probability of temporary and long-term disability, households can implement proactive safeguards—ranging from proper insurance structuring to diversified income generation—ensuring long-term economic resilience in the face of unforeseen medical challenges.
Related posts: