The Architect of Evolution: How Scott Sanborn Transformed LendingClub into Happen Bank

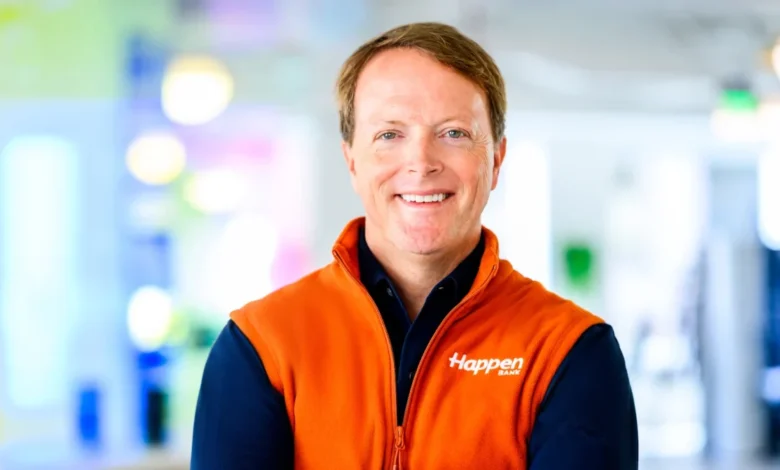
The history of modern fintech is often written in the language of disruption, but the story of Scott Sanborn’s tenure at what is now Happen Bank is one of stabilization, structural evolution, and institutional maturation. Over the course of a decade, Sanborn guided a prominent online lending marketplace through a governance crisis, a global pandemic, and a fundamental shift in business model, ultimately culminating in the 2026 rebranding from LendingClub to Happen Bank. This transition represents more than a mere name change; it signifies the successful convergence of agile, technology-first finance with the regulatory and capital-based stability of a traditional national bank.
The Evolution of a Fintech Giant: A Chronology
The trajectory of the company began in 2010 when Scott Sanborn joined as Chief Marketing Officer. At the time, the firm was a nascent player in the peer-to-peer lending space, tasked with the uphill battle of convincing consumers that non-traditional lending could be safer and more efficient than legacy banking. Between 2010 and 2016, Sanborn served in various leadership capacities, including Chief Operating Officer and President, during which time he helped oversee the company’s 2014 Initial Public Offering.
However, 2016 marked a defining pivot point. Following a governance crisis that shook investor confidence, Sanborn assumed the role of CEO. His mandate was clear: restore trust while navigating a market that was increasingly skeptical of monoline fintech lenders reliant on volatile, episodic outside funding. Recognizing that mere operational stabilization would be insufficient for long-term survival, Sanborn initiated a multi-year strategy to integrate the company’s marketplace model with the structural advantages of a national bank charter.
The cornerstone of this strategy was the 2020 acquisition of Radius Bank. Executed amidst the economic uncertainty of the COVID-19 pandemic, the acquisition was a bold gamble that transformed the firm into the first U.S. public fintech to operate as a nationally chartered bank. By 2021, the integration was complete, providing the company with the ability to hold loans on its own balance sheet and tap into a stable base of consumer deposits. By 2026, the company had fully shed its LendingClub identity, rebranding as Happen Bank to reflect its status as a comprehensive financial institution rather than a specialized lender.
Strategic Resilience and Financial Performance
The decision to acquire a bank charter provided the company with a significant competitive buffer during the high-interest-rate environment of 2022 and 2023. As market volatility impacted the cost of capital, many pure-play fintechs struggled with liquidity constraints. Happen Bank, conversely, leveraged its banking status to develop proprietary funding structures, such as the HAPS (structured certificates) and LENDR programs.
These initiatives have been instrumental in maintaining the company’s growth trajectory. Data indicates that within three years, these structured programs supported over $10 billion in loan sales. Furthermore, the company’s commitment to credit discipline—a hallmark of Sanborn’s leadership—has resulted in delinquency rates consistently 40% lower than the industry average for more than six years. This performance has positioned the bank as a preferred counterparty in the asset-backed securities market, even during periods of broader economic contraction.
The Shift from Transactional to Relational Banking
The transition from LendingClub to Happen Bank was not merely aesthetic; it was an attempt to change the nature of the consumer relationship. For years, the LendingClub brand was synonymous with single-use personal loans—a transactional relationship that ended once the debt was satisfied. Sanborn’s vision for Happen Bank centers on the "Motivated Middle," a demographic of high-FICO, digitally savvy consumers.

To facilitate this, the company launched the LevelUp suite of products. These products incentivize positive financial habits, such as on-time loan repayments and systematic savings. The impact has been measurable: 60% of new checking accounts are opened by existing borrowers, and loan payments made through Happen Bank internal accounts have increased by 700%.
The success of the LevelUp Savings product is perhaps the most telling metric of the company’s evolution. Currently holding over $4 billion in deposits, the product rewards users who maintain a monthly savings threshold of $250. According to company data, one in five LevelUp Savings account holders are former borrowers who have successfully transitioned from debt consolidation to wealth accumulation, building savings of between $18,000 and $20,000. This data point underscores a fundamental shift: Happen Bank has effectively moved from being a provider of debt to a partner in financial stability.
Industry Analysis: The Price of the Charter
The "Transformation Leader" award bestowed upon Sanborn at Tearsheet’s inaugural Vision Awards serves as an industry acknowledgement of the risks inherent in his strategy. While other fintechs have attempted to follow the path of charter acquisition, few have done so with the same level of regulatory success and operational integration.
Analysts point out that the regulatory "lift" required to manage a national bank charter is substantial. It requires a permanent commitment to compliance, capital adequacy, and rigorous risk management. Sanborn has frequently noted that the barriers to entry for this model are higher than most in the fintech sector anticipate. The integration of AI into these governance and operational frameworks further demonstrates the company’s commitment to modernization, utilizing new technology to manage the increased complexity of a banking structure without sacrificing the agility that characterized the company’s early years.
Implications for the Future of Fintech
The rebranding to Happen Bank represents a broader industry trend: the "bank-ification" of fintech. As the initial excitement of the 2010s-era "disruption" gives way to the realities of market maturity, the institutions that survive are those that can provide the depth of service and security of a bank alongside the user experience of a tech company.
The implications of Sanborn’s strategy are significant for the sector. By proving that a marketplace lender can successfully transition to a deposit-funded bank model, Happen Bank has created a template for other players in the industry. However, the success of this template depends heavily on the culture of the organization. Sanborn’s early focus on establishing core values—specifically the directive to "Do What’s Right"—has acted as a cultural anchor, preventing the company from losing its consumer-centric focus while navigating the rigid requirements of banking regulations.
Looking ahead, the challenge for Happen Bank will be sustaining this growth in a landscape where traditional banks are also investing heavily in their own digital transformations. With a deposit base now exceeding $10 billion and a diversified product suite, the institution is no longer a peripheral player in the financial ecosystem but a central one.
The transition from LendingClub to Happen Bank serves as a case study in institutional evolution. It is a reminder that the most effective way to change an industry is not necessarily to burn down existing structures, but to integrate the best of innovation with the enduring, necessary stability of the banking system. Scott Sanborn’s tenure has been defined by the recognition that while technology can change how a business operates, trust remains the primary currency of the financial world. As the bank enters this new chapter, its ability to maintain that trust while scaling its digital-first offerings will likely dictate its position in the next decade of financial services.
Related posts: