Ally Financial Expands Digital Banking Strategy With Fee-Free Loyally Rewards Program to Capture Gen Z and Millennials

Detroit-based Ally Financial is intensifying its push for primary customer relationships through the official nationwide rollout of "Loyally," a fee-free rewards experience designed to bridge everyday consumer spending, traditional saving, and modern investing. The launch follows a pilot phase earlier this year and signals a strategic evolution for the digital-first lender as it seeks to move beyond its foundational reputation as a high-yield savings vehicle.
The introduction of Loyally comes at a time when competition within the consumer banking sector has intensified. Financial institutions across the United States are increasingly looking for ways to foster customer loyalty and retention in an environment marked by shifting interest rates, rising digital expectations, and aggressive competition from both legacy institutions and financial technology firms. By offering customized perks, wellness-focused advantages, and cross-product incentives without imposing subscription fees or balance minimums, Ally aims to cement its status as an indispensable financial partner for its growing client base.
Evolution From High-Yield Pioneer to Everyday Financial Hub
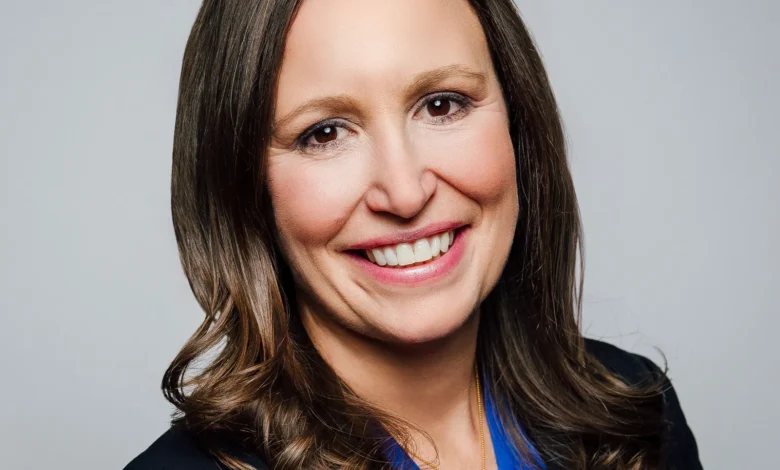
Ally’s journey into the consumer banking space was originally defined by its high-yield savings offerings, which helped the digital bank establish a loyal and sizable following. However, as consumer habits evolve, leadership at the institution recognized the necessity of expanding its relevance into daily financial management. According to Lindsay Sacknoff, Ally’s president of consumer banking, the overarching goal is to leverage the legacy built by its savings products to capture a larger share of customers’ everyday spending and long-term investing activities.
The Detroit-based lender officially announced the broad rollout of the Loyally program on a Tuesday, following a successful pilot phase deployed earlier in the year that allowed the bank to refine the user experience. Retail bank customers can now access a curated suite of rewards regardless of their account balances, removing traditional barriers that often lock lower-balance customers out of premier banking perks.
The program’s design reflects a careful analysis of consumer behavior, particularly how clients utilize savings mechanisms for lifestyle needs. For instance, noting that customers frequently use specialized savings buckets for pet care and personal wellness, Ally integrated everyday perks from brands such as Calm and Airvet into the Loyally ecosystem. Furthermore, the program incorporates experiential rewards, granting users opportunities to win tickets to high-profile concerts and sporting events.
A Broader Trend Across the Retail Banking Landscape
Ally is far from alone in its quest to revamp customer retention strategies through structured rewards programs. Across the banking sector, major financial institutions have recognized that traditional product-based differentiation is no longer sufficient to secure customer primacy.
Earlier this year, institutions such as Bank of America and PNC rolled out revamped or entirely new rewards initiatives tailored to meet the changing expectations of modern consumers. These moves underscore a broader industrywide push by lenders to deepen customer relationships, increase cross-product adoption, and reduce churn in a highly commoditized deposit market.
For Ally, the stakes are substantial. The bank’s retail division reported approximately 3.6 million customers as of the second quarter, representing a 7% increase compared to the same period in the previous year. Furthermore, the institution commands roughly $144 billion in total deposit balances within its retail bank, serving as a critical foundation for the broader $199.7 billion-asset parent company.
Capturing the Next Generation of Digital Natives
A cornerstone of Ally’s growth strategy involves capturing younger demographics, specifically Generation Z and millennials. According to Sacknoff, approximately 75% of the bank’s new checking and savings account holders belong to these younger cohorts. Furthermore, these digital-native generations demonstrate the highest utilization rates of the newly launched Loyally program.
Younger consumers tend to make financial decisions based heavily on personal values and corporate alignment. Recognizing this trend, Ally has leaned into its established "do it right" ethos. The bank’s commitment to equal sponsorship of men’s and women’s sports leagues has created a synergistic connection with younger cohorts who prioritize equity and inclusivity.
In its marketing and branding efforts, Ally has frequently positioned itself as a modern alternative to traditional brick-and-mortar institutions. By drawing contrasts with legacy branch networks, the digital lender markets itself as a technology-forward enterprise backed by the security and regulatory protection of a fully regulated bank. This positioning is particularly resonant among younger consumers who prefer app-based financial management over physical branch visits.
Navigating the Competitive Landscape of Digital Finance
The launch of the Loyally program also arrives at a critical juncture in the evolution of the broader fintech and banking ecosystem. While digital banks and fintech startups have historically operated outside the traditional regulatory perimeter—often partnering with chartered banks to offer services—the regulatory climate has prompted many fintech entities to pursue their own banking charters.
For example, major fintech players have pursued acquisitions of their partner banks to secure direct charter status, reflecting a growing desire for structural independence. In response, established digital institutions like Ally emphasize their heritage as the "original digital disruptor." Sacknoff and other executives maintain that Ally’s core advantage lies in its ability to channel the efficiencies of a digital-first model directly back into competitive savings rates and fee-free services, rather than maintaining expensive physical branch infrastructures.
Despite the rise of specialized apps, Ally is striving to be an all-encompassing financial home. By connecting spending, saving, and investing under a single digital roof, the bank has observed tangible results: customers who actively engage with the bank’s loyalty offerings are twice as likely to utilize both deposit and investment products compared to single-product users.
Strategic Personalization and Data-Driven Insights
A defining characteristic of the Loyally program is its emphasis on intelligent personalization. Rather than deploying a one-size-fits-all rewards structure, Ally utilizes data insights to present relevant offers based on individual customer behavior and financial trajectories.
For example, a consumer who actively uses the bank’s spending and saving accounts may be presented with a targeted bonus offer or educational prompt to open an Ally investing account. This cross-selling mechanism is designed to feel organic rather than intrusive, guiding customers naturally along a continuum of financial wellness.
This advisory-oriented approach aligns with the demographics of Ally’s existing customer base. Approximately two-thirds of the bank’s retail customers report an annual household income of $75,000 or more, representing an economically stable segment that values comprehensive financial tools.
Sacknoff noted that the bank’s suite of digital offerings—including goal-based savings buckets, integrated credit score monitoring, and advanced cash-flow visibility tools from a spending perspective—serve as critical differentiators in the marketplace. Rather than competing solely on interest rates or superficial promotions, Ally seeks to embed itself in customers’ daily financial lives by providing actionable insights that help them achieve their long-term monetary goals.
Looking Ahead: Long-Term Commitment and Program Evolution
While Ally has declined to publicly disclose the exact financial capital allocated toward developing and launching the Loyally program, company representatives have described the initiative as a long-term strategic commitment. The emphasis is squarely on sustainable engagement rather than short-term acquisition metrics.
As the program matures, Ally plans to continuously evaluate user engagement patterns and transaction data to refresh its catalog of rewards and experiential offerings. Recent enhancements—such as partnerships that allow customers to deposit cash through major retail networks like Walmart—demonstrate the bank’s willingness to adapt its operational footprint to meet consumer demands for physical-digital integration.
Ultimately, the success of the Loyally program will be measured by its ability to drive primary bank status—ensuring that Ally is not merely a secondary parking spot for high-yield savings, but the central financial hub where consumers manage their daily income, discretionary spending, and wealth accumulation strategies. As retail banking margins tighten and customer acquisition costs rise, initiatives that successfully foster cross-product engagement and brand affinity will likely define the leaders of the next era of consumer finance.