The modern financial independence, retire early (FIRE) movement is frequently framed as a linear mathematical equation: accumulate a specific multiple of your annual expenses, and you are free to leave the workforce permanently. However, a granular examination of career trajectories, lifestyle inflation, and macroeconomic realities suggests that the psychological and structural barriers to exiting the workforce compound significantly with age. Retiring in one’s mid-thirties, counterintuitively, often presents a lower risk profile and greater operational flexibility than attempting the same transition at age fifty.
This paradox challenges conventional retirement planning dogma, which traditionally assumes that higher net worth and advanced career tenure equate to a frictionless exit. Historical case studies, labor market dynamics, and the subtle mechanics of golden handcuffs reveal that early-stage financial independence offers distinct structural advantages that vanish by mid-career.
The Mechanics of the 2012 Departure
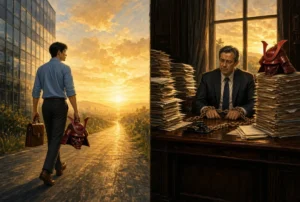
To understand the asymmetry between retiring at 35 versus 50, it is instructive to examine the baseline conditions of early exits. In 2012, a prominent financial commentator and former investment banking executive intentionally engineered his departure from a 13-year career in the financial sector just two months before his 35th birthday. At the time, the move was perceived as an extreme vocational risk—walking away precisely when individual earning power typically enters its most lucrative decade of compounding returns.
Retrospectively, the structural risk of that departure was cushioned by several key factors common to young professionals: minimal fixed familial overhead, the absence of dependent children, and a resilient macroeconomic recovery phase that still valued transferable white-collar skills. Individuals who execute a FIRE strategy in their early-to-mid-thirties typically have a shorter history of lifestyle inflation. Their baseline cost of living remains low, meaning their required corpus to sustain early retirement is fractionally smaller than that of a mid-career corporate officer.
Furthermore, empirical observations of professionals who leave demanding corporate tracks in their early thirties demonstrate a high degree of career optionality. Data tracking early retirees who attempt secondary passions—such as culinary arts or digital media—reveals that a significant percentage can successfully re-enter the traditional labor market within 12 to 24 months if their early retirement thesis fails to materialize.
The Escalating Trap of Mid-Career Compensation
In sharp contrast, retiring at age 50 involves navigating a vastly different financial and psychological landscape. By the fifth decade of life, successful professionals in high-income sectors such as finance, technology, and management have usually achieved senior ranks, such as Managing Director or equivalent executive status. At this tier, total compensation packages frequently combine a substantial base salary with highly lucrative, performance-based discretionary bonuses and deferred equity vesting schedules.
Walking away from a total compensation package that may easily range between $500,000 and $2.5 million annually creates a profound psychological barrier. This phenomenon, widely recognized in labor economics as the golden handcuffs, intensifies over time rather than slackening. As earning potential peaks, the perceived cost of abandonment scales exponentially, making the decision to walk away an exercise in severe financial fortitude.

Compounding this income effect is lifestyle inflation. Over a 20-year career, households naturally scale their fixed expenditures to match their elevated earnings. Premium real estate holdings, private educational tuition for dependents, specialized domestic services, and the overarching goal of establishing multi-generational wealth transform the household balance sheet. Maintaining these commitments without a continuous stream of high-bracket W-2 income introduces acute financial vulnerability, compelling workers to extend their employment tenure despite declining job satisfaction.
Macroeconomic Realities and Labor Market Re-Entry
A critical variable often overlooked in early retirement planning is the asymmetry of labor market re-entry across different age brackets. A 34-year-old professional who tests the waters of retirement and decides to return to the workforce possesses a high degree of market desirability. Employers view younger candidates as adaptable, digitally fluent, and capable of enduring rigorous corporate workloads over a long-term horizon.
Conversely, professionals attempting to re-enter the knowledge economy at age 50 face significant structural headwinds. Structural shifts, including the rapid integration of artificial intelligence and automated workflow systems, have compressed entry-level and mid-level demand for traditional white-collar roles. Simultaneously, age-related biases within corporate hiring practices disproportionately affect executive-tier applicants.
| Metric | Retiring at Age 35 | Retiring at Age 50 |
|---|---|---|
| Typical Compensation Forgone | Moderate ($150,000 baseline) | Substantial ($350,000 to $2,500,000+) |
| Primary Dependents | Generally self or spouse only | Children, spouse, and aging parents |
| Re-Entry Velocity | High; typically within 12 months | Low; restricted executive market |
| Fixed Lifestyle Overhead | Minimal and easily compressible | Fully expanded and rigid |
| Employment Recovery Buffer | Decades of high earning runway remaining | Limited runway prior to traditional retirement |
Consequently, a professional executing a FIRE strategy at age 50 must view the transition as an irreversible crossing of the Rubicon. The safety net of returning to corporate life to repair a depleted portfolio is largely absent, requiring absolute certainty regarding portfolio longevity and market performance.
Familial Obligations and Eldercare Pressures
The demographic realities of mid-life further complicate the execution of retirement strategies. While a 35-year-old typically answers only to themselves, a 50-year-old is often caught in the demographic squeeze of the "sandwich generation." This involves simultaneously funding collegiate or preparatory education for adolescent children while allocating significant financial resources toward the emerging eldercare needs of aging parents.
Recent macroeconomic analyses underscore the escalating costs of long-term care and higher education, both of which have outpaced general consumer inflation indices over the past three decades. The responsibility of safeguarding family members against future economic volatility creates an inherent instinct to over-save and over-work. Ironically, while the foundational goal of FIRE is personal autonomy, the accumulation of familial obligations as one ages often renders the pursuit of multi-generational financial security incompatible with early exit strategies.
Strategic Implications for Wealth Accumulation
The evolving friction of aging challenges the traditional premise that early retirement becomes progressively easier as net worth expands. While mathematical models focus exclusively on asset accumulation and safe withdrawal rates, human behavior and systemic economic variables dictate that the friction of exit scales in tandem with portfolio size.
Financial planners and career strategists analyzing modern workforce trends suggest that individuals serious about achieving absolute independence should target transitions during phases of high professional resilience—ideally prior to the onset of heavy fixed domestic liabilities and peak lifestyle inflation. For those who find themselves navigating the corporate hierarchy past age 45, the decision to leave requires rigorous stress-testing of not just investment portfolios, but psychological tolerance for absolute permanence and diminished re-employment prospects.