European Markets Rally as France Sidesteps Moody’s Downgrade, While Brussels Weighs New Safeguards Against Chinese Imports

European financial markets found temporary respite at the start of the week, buoyed by positive developments in France that averted a looming sovereign credit downgrade and a general stabilization of political tensions. Last Friday delivered a double dose of good news for French fiscal sentiment: the nation successfully sidestepped a potentially damaging rating downgrade by Moody’s, while weekend demonstrations across major metropolitan areas shifted into a markedly less aggressive gear.
This dual development proved to be a critical circuit breaker, effectively halting the severe EMU credit spread widening that plagued bond markets throughout the preceding week. The market relief was immediately visible across European debt instruments. The 10-year OAT (Obligations Assimilables du Trésor) swap spread ceded 8 basis points from its Friday closing mark, settling at approximately 147 basis points. Similarly, the 10-year OLO (Obligations Lineaires / Linear Bonds) swap spread contracted by 4 basis points to rest at 93 basis points.
Despite the calming of French debt dynamics, idiosyncratic pressures persisted elsewhere in the eurozone. In Belgium, protracted budget negotiations remained deadlocked, with the majority of governing coalition parties openly pointing fingers at the Flemish Socialist party, Vooruit, accusing them of taking the fiscal process hostage despite mounting market pressures. Belgian Prime Minister Bart De Wever had initially targeted a comprehensive fiscal agreement by Halloween. However, political realities have forced a recalibration, with rumors circulating that the Prime Minister is prepared to extend his self-imposed deadline to November 3.
Adding to the domestic supply dynamics, the Belgian debt agency capitalized on the window of stability by raising the maximum target of €2.8 billion during its regular monthly OLO auction, successfully extracting bids within its €2–€2.8 billion range. The auction featured three distinct lines: €0.9 billion of the 3% June 2033 OLO 97, €1.3 billion of the 3.4% June 2036 OLO 106, and €0.6 billion of the 0.4% June 2040 OLO 90. With an aggregate bid-to-cover ratio hovering slightly above 1.6, the meticulous execution of the sale allowed the Belgian debt agency to nearly finalize its total 2026 OLO funding requirement, bringing its cumulative tally to €51.6 billion against a projected annual need of €50.45 billion.
The Currency Conundrum and Escalating Energy Pressures
In the foreign exchange markets, the single currency displayed a curious resilience, failing to profit meaningfully from the easing of French sovereign risks, much in the same way it had managed to evade severe structural damage during the previous week’s credit widening episodes. The EUR/USD pair initially attempted to claw its way back above the psychologically significant 1.12 handle during early European trading, but quickly surrendered those gains to hover near the 1.1180 mark.
Underpinning this currency behavior are mounting macroeconomic headwinds, most notably the relentless surge in European energy prices. Natural gas costs have re-emerged as a primary catalyst for concern within the single currency bloc. The benchmark Dutch TTF (Title Transfer Facility) front-month reference contract approached the €100/MWh threshold during the session—a psychological and financial milestone not witnessed since the tail end of 2022. This resurgence in energy commodity pricing threatens to reignite imported inflation, complicating the broader macroeconomic landscape for businesses and households alike as the winter heating season approaches.
Broader risk sentiment across global equities, however, painted a brighter picture. Main European bourses and major United States stock indices climbed by as much as 1% during the session, reflecting a general appetite for risk assets that momentarily overshadowed underlying structural anxieties. Economic data releases offered little in the way of directional inspiration; the closely watched German Ifo business sentiment survey printed figures that closely mirrored the subdued manufacturing and services PMIs recorded the prior week, confirming a protracted stagnation within the eurozone’s economic powerhouse.
Central Bank Conundrums Ahead of High-Stakes Policy Meetings
Market participants are swiftly shifting their focus toward an action-packed macroeconomic calendar later in the week, headlined by high-stakes monetary policy deliberations from both the United States Federal Reserve and the European Central Bank (ECB). While consensus expectations point toward both central banks defending the status quo and maintaining current policy rates, persistent underlying price pressures may compel policymakers to abandon their previously signaled gradualist approaches.
Financial analysts widely anticipate that both the Fed and the ECB will adopt an explicitly hawkish rhetorical posture. Their primary objective will be to anchor long-term inflation expectations and prevent them from drifting uncomfortably upward in the face of sticky services inflation and volatile commodity inputs.
This impending policy stance is expected to find validation in upcoming tier-one economic indicators. Analysts flag substantial upside risks for both the United States September Personal Consumption Expenditures (PCE) deflator prints and the preliminary national Consumer Price Index (CPI) readings across major eurozone economies for October. Furthermore, initial third-quarter Gross Domestic Product (GDP) estimates are projected to underscore economic resilience within the eurozone, alongside continued, relative economic outperformance by the United States.
Czech Business and Consumer Confidence Retreats to Multi-Month Lows
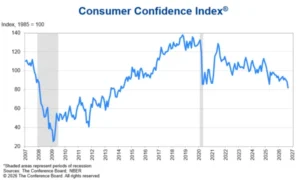
Beyond the core eurozone economies, regional indicators highlighted persistent fragility in Central and Eastern Europe. The Czech composite confidence indicator experienced a sharper-than-anticipated contraction in October, sliding from 99.5 to 97.9 to touch its lowest level since April 2025.
A granular breakdown of the survey data reveals broad-based weakness across both primary components. The business confidence sub-index plummeted by 1.8 points to settle at 96.6, matching its joint-lowest reading in two years. The industrial manufacturing sector bore the brunt of the contraction, registering a precipitous monthly drop of 5.6 points. The trade sector followed with a decline of 1.7 points, while construction activity dipped by a more modest 0.6 points. Conversely, selected service industries managed to swim against the current, eking out a modest 2-point gain.
Consumer confidence within the Czech Republic mirrored the business gloom, edging lower by 0.8 points to 104.3. Households expressed mounting pessimism regarding the broader macroeconomic environment, with a higher proportion of respondents anticipating economic deterioration over the upcoming twelve-month horizon. While the percentage of consumers assessing their current personal financial situation as worse than the previous year experienced a slight downward tick, overall household appetite for major capital expenditures and durable goods over the next twelve months diminished notably.
The Czech crown remained relatively stable in the immediate window following the data publication but lost ground on a broader daily perspective, with the EUR/CZK exchange rate hovering near the 24.37 threshold.
Brussels Prepares Aggressive Trade Safeguards Against Chinese Imports
In trade policy developments that threaten to strain diplomatic ties between Brussels and Beijing, the European Commission is pressing ahead with targeted safeguard measures designed to curtail surging imports from China across critical industrial sectors, including chemicals, furniture, and advanced machinery. According to individuals closely familiar with the matter, these protective mechanisms will primarily take the form of restrictive import quotas—echoing the recently enacted annual ceiling of 350,000 units on Chinese hybrid electric vehicles—alongside punitive import tariffs.
These deliberations follow preliminary investigative reports from Bloomberg indicating that European Union trade officials have already initiated comprehensive analyses of cross-border trade flows. The explicit objective is to uncover definitive statistical evidence of an import surge within specific manufacturing verticals, which serves as the strict legal and procedural precondition required under EU trade law for the implementation of safeguard mechanisms.
More broadly, the executive arm of the European Union is seeking to establish sweeping new legislative powers. These structural tools are intended to assist member states in actively curbing ballooning bilateral trade deficits while simultaneously serving as a credible deterrent against perceived non-market trade practices and overcapacity issues originating from Asian manufacturing hubs. Concrete, formal policy proposals detailing these safeguard mechanisms and enforcement powers are anticipated to be unveiled by the European Commission prior to mid-December, setting the stage for what promises to be a contentious winter of trade diplomacy.