Bridging the Credit Gap: How Cash Flow Data and the UltraFICO Score are Redefining Financial Inclusion

The modern global economy is undergoing a profound structural transformation in how individuals earn, manage, and spend money. Traditional employment models—characterized by steady, salaried 9-to-5 jobs with regular bi-weekly paychecks—are increasingly sharing the stage with a dynamic, decentralized workforce. Today, millions of workers participate in the gig economy, operate as independent freelancers, engage in seasonal labor, or manage multiple micro-enterprises. While this evolution has introduced unprecedented professional flexibility, it has simultaneously exposed a glaring structural flaw in the traditional financial ecosystem: the rigid architecture of consumer credit assessment.
For decades, evaluating a borrower’s creditworthiness relied primarily on legacy credit reports. These reports meticulously track historical debt obligations, loan repayments, and credit card histories. However, they frequently fail to capture the holistic financial reality of modern earners whose income streams fluctuate month-to-month. This systemic oversight has historically marginalized millions of credit-invisible, unbanked, or underbanked consumers. Fortunately, a transformative wave of financial technology innovation, coupled with a fundamental shift in how lenders define financial risk, is actively dismantling these barriers.
At the forefront of this movement is FICO, a foundational pillar of consumer credit scoring, which used the stage at FinovateFall 2026 to showcase how modern data integration is reshaping the lending landscape. Through strategic initiatives like the UltraFICO Score—developed in high-profile partnership with financial data network Plaid—the industry is beginning to bridge the gap between traditional credit metrics and real-time financial behavior.
Understanding the Dichotomy: Ability to Pay Versus Willingness to Pay
To comprehend the significance of incorporating cash flow data into credit scoring, industry experts emphasize the need to distinguish between two fundamental pillars of lending risk: willingness to pay and ability to pay. Speaking at FinovateFall 2026, Jaron Murphy, Head of Partnerships at FICO Scores, articulated this distinction with surgical precision.
"When you look at credit data and the credit report, it really shows what I call ‘willingness to pay,’" Murphy explained during his featured discussion. "It’s looking at behavior to understand how willing the consumer is, based on past behavior and debt obligations, to repay this debt."
For nearly seventy years, traditional credit scores have excelled at measuring this exact psychological and behavioral commitment. By analyzing how a consumer has historically handled credit cards, mortgages, and auto loans, lenders can infer whether that individual prioritizes debt repayment.
However, Murphy highlighted the critical missing link that has historically locked millions of reliable consumers out of the formal credit market: "There’s another part that’s always been missing though, and it’s that cash flow aspect. It’s the ability to pay, not just the willingness, but what is the consumer’s ability to pay, as well? That’s what really excites me about where we’re at today is being able to leverage cash flow data to understand consumers in new ways. And that’s what we’ve been embarking on."
By combining traditional credit reports with granular, permissioned cash flow data—such as checking and savings account balances, cash inflows, and consistent utility or rent payments—lenders gain a 360-degree view of an applicant’s financial health. This methodology ensures that individuals who may lack a deep traditional credit history, yet maintain healthy bank balances and consistent cash reserves, are no longer unfairly penalized by outdated risk models.
The Evolution of FICO: A Legacy of Analytics Meeting Modern Innovation
To appreciate the trajectory of modern credit scoring, it is instructive to examine the institutional evolution of FICO. Founded in 1956 and headquartered in Bozeman, Montana, the company originally known as Fair, Isaac and Company pioneered the use of predictive analytics and data science to help businesses make complex operational decisions. Over the subsequent decades, FICO transformed from a boutique consultancy into an indispensable infrastructural backbone of the global financial system.
Today, FICO solutions are utilized across multiple commercial sectors, helping institutions defend against sophisticated financial fraud, advance regulatory compliance, enhance enterprise risk management, and dramatically improve credit access and transparency. Most notably, the flagship FICO Score remains the definitive standard measure of consumer credit risk in the United States, trusted and utilized by 90% of the top U.S. lenders for underwriting decisions.
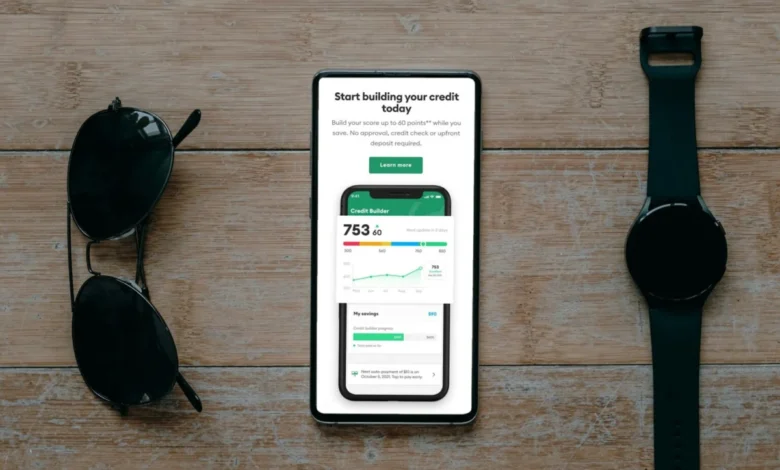
Despite its dominant market share, the company has recognized that maintaining the status quo is insufficient in an era of rapid economic disruption. As consumer banking behaviors migrated online and smartphone applications democratized personal finance management, FICO embarked on a strategic campaign to modernize its scoring models. The centerpiece of this modernization effort is the UltraFICO Score, an opt-in credit scoring model designed to safely factor consumer banking history into traditional credit risk evaluations.
The Plaid Partnership: Unlocking Real-Time Financial Visibility
The operational engine driving modern cash flow underwriting is connectivity, and FICO’s strategic partnership with Plaid—which took major strides earlier this year—represents a watershed moment for open banking integration. Plaid’s secure API infrastructure allows consumers to seamlessly and securely link their primary checking and savings accounts directly to credit applications with explicit, real-time consent.
Through this integration, the UltraFICO Score evaluates positive cash flow behaviors that were previously invisible to major credit bureaus. These positive indicators include:
- Maintaining positive account balances over extended observation windows.
- Avoiding frequent overdraft fees or negative balances.
- Demonstrating consistent patterns of discretionary savings deposits.
- Regularly paying recurring non-credit obligations, such as telecommunications bills, utility services, and residential rent.
When a consumer with a thin credit file—or a consumer recovering from past financial missteps—opts to share their banking data, the algorithm recalibrates. In many instances, this cash flow augmentation elevates borderline applicants above underwriting thresholds, granting them access to prime or near-prime interest rates. For lenders, this capability expands addressable markets without compromising risk tolerances; for consumers, it establishes a direct pathway to lower borrowing costs and improved financial mobility.
The Broader Economic Impact and Financial Inclusion Implications
The integration of cash flow data into mainstream credit scoring carries profound economic implications that extend far beyond individual loan approvals. For decades, financial inclusion advocates have argued that traditional credit metrics perpetuate cycles of economic inequality. Consumers without generational wealth or access to traditional revolving credit lines often find themselves trapped in a catch-22: they cannot secure credit because they lack a credit history, and they cannot build a credit history because they cannot secure credit.
By validating "ability to pay" through everyday banking transactions, financial institutions can safely extend credit to historically underserved demographics. This includes younger consumers entering the workforce, recent immigrants establishing financial roots, rural populations with limited physical banking access, and gig economy workers whose variable earnings defy traditional underwriting parameters.
Furthermore, expanding credit access through robust data analytics stimulates broader economic activity. Access to fairly priced credit empowers consumers to purchase reliable transportation for employment, invest in higher education, secure small business capital, and finance residential real estate. In aggregate, these micro-level financial inclusions aggregate into macro-level economic resilience and growth.
Looking Ahead: The Future of Consumer Lending
As demonstrated during FinovateFall 2026—where FICO participated as a prominent Grade 4 sponsor—the financial technology sector is moving decisively toward an era of hyper-personalized, data-driven underwriting. The dialogue led by executives like Jaron Murphy underscores a collective industry realization: the future of credit risk assessment lies not in replacing traditional data, but in enriching it.
As strategic partnerships between legacy credit giants and nimble open-banking networks mature, the boundaries of financial inclusion will continue to expand. By harmonizing a consumer’s historical willingness to pay with their real-time ability to pay, the financial system is moving closer to an ideal where every honest, hardworking individual is accurately evaluated, fairly priced, and fully integrated into the modern economy.
Related posts: