American Express Expands Business Banking Suite with High-Yield Savings, Rewards Redemption, and Gusto-Powered Payroll Solutions

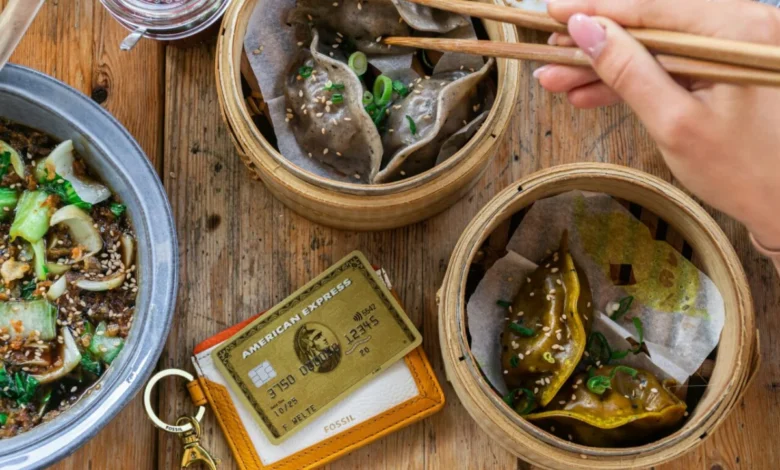
American Express has announced a major expansion of its commercial banking ecosystem, introducing a high-yield business savings account, enhanced rewards-to-checking redemptions, and an upcoming integrated payroll solution powered by Gusto. This strategic rollout is designed to deepen the financial services American Express provides to small and mid-sized enterprises (SMEs), positioning the legacy financial giant more directly against a crowded field of digital-first fintech platforms and traditional financial institutions vying for the primary operating account status of growing businesses.
The centerpiece of the latest announcement is the launch of the American Express Business Savings account, which offers a competitive annual percentage yield (APY) of 2.95%. Crucially for growing businesses managing fluctuating cash flows, the account features no minimum balance requirements and does not charge monthly maintenance fees. Account holders can execute and receive transfers online or via the proprietary Amex mobile application, with the added benefit of instant, fee-free transfers between the new savings vehicle and existing American Express Business Checking accounts.
Strategic Enhancements to Cards and Cash Flow Management
Beyond the high-yield savings product, American Express is rolling out targeted feature integrations throughout the year to bridge the gap between commercial credit and core banking functions. Later this year, members utilizing the Graphite Business Cash Unlimited card—which offers a flat 2% cash back reward on every transaction—will gain the ability to seamlessly redeem their earned reward dollars directly as cash deposits into their Business Checking accounts. This integration aims to create a tighter loop between everyday corporate spending and liquidity management, providing tangible value back to business owners without requiring complex redemption processes.
Furthermore, American Express is addressing a critical operational pain point for business owners by introducing a fully integrated payroll solution powered by Gusto. Slated for an early next year launch following an initial preview period later this year, the service will be made available to Business Checking customers for a modest monthly fee. The functionality allows businesses to enroll, manage, and execute payroll directly within the American Express Business Checking interface, centralizing administrative duties into a single dashboard. Leveraging Gusto’s technological infrastructure, the system will also deliver artificial intelligence-powered insights on payroll trends, labor costs, and tax compliance to help business owners optimize their workforce expenditures.
The Evolution of Amex Business Membership
These new product introductions represent the continuous evolution of the Amex Business Membership model, a broader initiative by the company to bundle value-add services for commercial clients. The newly introduced tools are engineered to integrate smoothly with third-party accounting software and link seamlessly with external bank accounts. By facilitating easier movement of funds and real-time financial tracking, American Express is targeting the administrative burden that frequently consumes the time of modern entrepreneurs and financial officers.
Eva Reda, Executive Vice President of Global Commercial Services at American Express, emphasized the changing expectations of commercial banking clients in the current economic climate. "Businesses are looking for more value from their banking services, including competitive returns and simple tools that help them automate processes and fit seamlessly into how they operate," Reda stated. "With Amex Business Banking, businesses now have banking tools that make it easy and rewarding to manage their finances, all in one place."
The Competitive Landscape in Business Banking
The aggressive expansion by American Express highlights a broader structural shift within the commercial financial services sector. For decades, traditional banking models relied on siloed product offerings, where a business might hold a corporate credit card with one institution, a checking account with another, and software subscriptions spread across various back-office vendors. However, the emergence of digital-first financial technology platforms—such as Mercury, Brex, and Bluevine—has fundamentally altered market expectations.
These fintech competitors have successfully captured market share by building comprehensive financial operating systems. By combining FDIC-insured deposit accounts with embedded expense management, automated corporate cards, instantaneous payment rails, and advanced accounting integrations, fintechs have raised the bar for what businesses expect from a financial services provider. Rather than functioning merely as a passive repository for corporate capital, modern business accounts are expected to actively assist in financial planning, cash flow optimization, and day-to-day administrative overhead.
American Express is strategically leaning into its legacy dominance in corporate and small business credit cards to counter this competitive threat. By leveraging its existing cardholder base as a foundational entry point, the company is systematically building out a complete banking ecosystem around them. Connecting card rewards directly to business checking, introducing competitive high-yield savings, and embedding robust payroll capabilities give enterprise clients fewer reasons to look outside the Amex network for their financial needs.
Broader Implications and Market Impact
Industry analysts note that the ultimate differentiator in the modern business banking wars is not any single metric, such as a 2.95% APY, but rather the depth of integration across platforms. As commercial banking providers continue to rebundle financial and back-office functions, the winners will be determined by their ability to eliminate friction. Businesses face constant pressure to reduce operational complexity and software bloat. Providers that successfully minimize the number of external systems an owner must juggle stand the strongest chance of securing long-term primary financial relationships.
For American Express, the strategy hinges on trust, brand recognition, and ecosystem stickiness. By transforming its product suite from a transactional card platform into an all-encompassing financial management hub, Amex is securing its relevance for the next generation of businesses. As these new features roll out over the coming months, the broader financial sector will be closely watching to see how traditional banking giants and nimble fintechs adapt to this increasingly integrated commercial banking frontier.