Coinbase and Stablecore Partner to Bring Digital Asset Services and Stablecoin Infrastructure to Over 3,000 Community Banks and Credit Unions

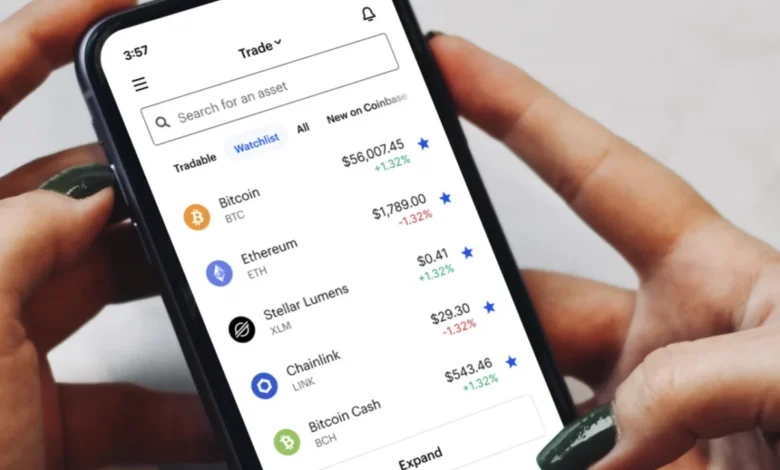
The intersection of traditional finance and the decentralized digital economy has reached a significant milestone. Cryptocurrency exchange giant Coinbase has officially announced a strategic partnership with Stablecore, a specialized banking infrastructure provider tailored for digital assets and decentralized finance (DeFi). This collaboration is designed to empower more than 3,000 community banks and credit unions across the United States to seamlessly offer regulated digital asset products, trading capabilities, secure custody solutions, and stablecoin payment options directly through their existing proprietary banking platforms.
For decades, the mainstream banking sector has operated on legacy infrastructure that largely isolated traditional financial institutions from the rapid innovations occurring in the digital asset landscape. As consumer demand for cryptocurrencies, blockchain-enabled cross-border payments, and tokenized financial instruments continues to surge, smaller financial institutions have frequently found themselves at a competitive disadvantage. They have historically lacked the capital, technical expertise, and regulatory frameworks required to build and maintain secure crypto-related infrastructure in-house.
The new alliance between Coinbase and Stablecore seeks to dismantle these systemic barriers. By integrating Coinbase’s institutional-grade digital asset capabilities with Stablecore’s modular, white-labeled banking middleware, regional financial institutions can now bridge the gap between legacy banking and Web3 technology without uprooting their foundational operations.
The Evolution of Stablecore and the Genesis of the Partnership
Founded in 2025, Stablecore quickly established itself as a pioneering force within the modern fintech ecosystem by focusing exclusively on the unique needs of community and regional banks as well as credit unions. Based in Texas, the fintech enterprise recognized that local financial institutions serve as the economic backbone of their respective communities, yet they risk losing market share to agile, digital-first neobanks and centralized crypto exchanges if they fail to modernize their service offerings.
Stablecore’s technological framework acts as an integration layer, unifying tokenized deposits, stablecoin transaction rails, and compliant digital asset products into a single, cohesive architecture. Rather than forcing banks to adopt disruptive, unproven operating systems, Stablecore enables them to launch these advanced capabilities under their own brand names and governance frameworks.
Under the terms of the newly finalized agreement, Coinbase will leverage its robust regulatory compliance, deep liquidity pools, and advanced security infrastructure to power the back-end requirements of Stablecore’s vast network. This means that bank customers and credit union members will soon be able to execute trades, hold digital assets securely, and utilize stablecoins for transactions without ever needing to navigate away from their primary online banking portal or mobile application.
Amarillo National Bank Leads the Vanguard
Among the primary financial institutions already participating in the pilot rollout of this digital asset offering is Amarillo National Bank, a prominent Texas-based institution with a deep-rooted history in community banking. By adopting the integrated Stablecore-Coinbase infrastructure, Amarillo National Bank is demonstrating how regional institutions can innovate proactively.
The implementation allows the bank to deliver state-of-the-art digital asset services on its own terms and under its trusted brand identity. Crucially, this setup ensures that vital customer relationships, deposit accounts, and lending portfolios remain localized within the community bank ecosystem rather than leaking out to third-party cryptocurrency platforms.
"Banks and credit unions should not have to move to completely new technology platforms to support digital assets for their clients," stated Stablecore Co-Founder and CEO Alex Treece. "We built Stablecore to bring together all of the pieces so they don’t have to."
This sentiment is strongly echoed by leadership at Coinbase, which has steadily expanded its footprint in the institutional and enterprise infrastructure space. Alec Lovett, Coinbase’s Head of Infrastructure Business, emphasized the strategic importance of empowering smaller financial institutions to maintain their competitive edge in an evolving macroeconomic environment.
"Community banks and credit unions shouldn’t have to choose between staying local and staying current," Lovett noted. "Together with Stablecore, we are helping put them on the cutting edge of payments technology—cheaper, faster money movement, and the tools they need to stay strong for the communities they serve."
The Broader Industry Trend: The Great Rebundling of Financial Services
To fully understand the significance of the Coinbase and Stablecore partnership, industry analysts point to a broader macro-trend currently transforming the global financial architecture: the rebundling of financial services.
During the formative years of the cryptocurrency industry, digital assets developed largely in silos, completely detached from the traditional banking sector. Consumers seeking exposure to Bitcoin, Ethereum, or stablecoins were required to establish independent, external relationships with specialized crypto exchanges, standalone digital wallets, and decentralized protocols. This fragmented user experience created operational friction, heightened security concerns for retail investors, and alienated mainstream consumers who preferred the convenience of unified account management.
In recent years, however, the financial services industry has entered a phase of consolidation and integration. Infrastructure providers and forward-thinking fintechs are actively working to bridge these previously disconnected ecosystems. By bringing advanced capabilities—such as yield generation, tokenized real-world assets, and instantaneous stablecoin settlement—directly back inside the traditional banking environment, companies like Stablecore are helping reverse financial fragmentation.
This strategic pivot offers community financial institutions a vital lifeline. As consumer demographics shift and younger generations demand comprehensive, tech-forward financial management tools, traditional banks and credit unions risk disintermediation. If a consumer’s primary financial relationship fails to support modern digital assets, that customer is increasingly likely to migrate their capital to digital-native fintech alternatives. The Coinbase-Stablecore integration directly combats this risk by enabling local institutions to serve as the singular hub for both fiat and digital wealth management.
A Paradigm Shift in Corporate Strategy: Infrastructure as a Service
One of the most compelling aspects of this partnership lies in its unconventional corporate strategy. As a dominant global cryptocurrency exchange, Coinbase maintains a direct-to-consumer platform that competes head-to-head with traditional banking apps for retail trading volume, custody fees, and payment transactions.
Historically, dominant fintech platforms have sought to capture and retain direct ownership of the end-user relationship at all costs. However, Coinbase’s ongoing expansion into B2B infrastructure signals a sophisticated evolution in corporate strategy. By making its proprietary capabilities accessible to traditional banks via middleware providers like Stablecore, Coinbase is choosing to monetize the underlying infrastructure of the financial system rather than exclusively fighting for front-end customer acquisition.
Under this model, if retail consumers increasingly prefer to access digital assets alongside their traditional checking, savings, and loan products within their trusted local bank app, Coinbase does not need to own the direct customer relationship. Instead, it captures substantial revenue by powering the plumbing behind the scenes.
For the banking sector, this arrangement offers an unprecedented opportunity to fortify their position as the central repository where everyday consumers manage their holistic financial lives. Rather than viewing the rise of decentralized finance as an existential threat to be resisted, participating community banks are transforming it into an organic extension of their legacy product suites.
Regulatory Compliance and Market Implications
As global regulatory scrutiny surrounding digital assets intensifies, security, anti-money laundering (AML) protocols, and know-your-customer (KYC) compliance remain paramount for institutional adoption. Community banks operate in a strictly regulated environment overseen by federal and state agencies, meaning that any integration of cryptocurrency products must adhere to the highest standards of safety and legal compliance.
Coinbase’s institutional reputation for regulatory rigor provides a crucial anchor of trust for participating banks. By utilizing infrastructure vetted by industry leaders, risk-averse institutions gain the confidence necessary to explore digital assets without exposing themselves to undue compliance vulnerabilities. Stablecore’s white-labeled framework ensures that all transactions maintain the stringent auditability and transparency required by banking regulators.
Looking forward, the successful deployment of this infrastructure across Stablecore’s network of more than 3,000 institutions could serve as a powerful catalyst for broader market adoption. If community banks and credit unions can efficiently roll out stablecoin payments and digital asset custody without encountering technological bottlenecks, it may pave the way for accelerated mainstream acceptance of tokenized finance throughout middle-America and regional economies.
Ultimately, the partnership between Coinbase and Stablecore highlights a transformative maturation within the financial technology sector. By bridging the gap between cutting-edge blockchain capabilities and legacy banking systems, the collaboration ensures that community financial institutions are not left behind in the digital asset revolution, effectively reshaping the future of modern banking infrastructure.