The Resilience of Global Trade in the Shadow of Trump’s Second-Term Tariffs

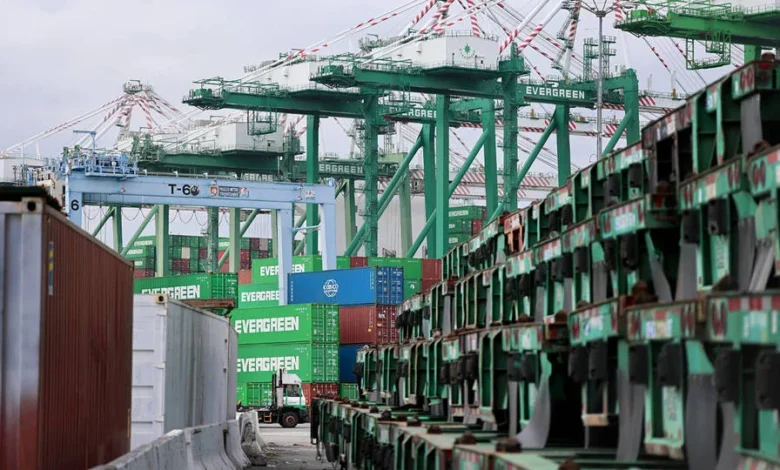
WASHINGTON, DC — Nearly two years have elapsed since Donald Trump assumed the presidency for a second term, marking a dramatic intensification of the protectionist trade policies that defined his initial years in office. Since returning to the White House, the administration has systematically dismantled pillars of the open multilateral trading architecture that has underpinned global economic growth and stability since the conclusion of the Second World War. By deploying sweeping and frequently shifting tariffs against dozens of trading partners, the executive branch has driven United States tariff rates to heights not witnessed since the enactment of the notoriously restrictive Smoot-Hawley Tariff Act during the Great Depression.
Despite the widespread disruptions predicted by economists, the broader architecture of global trade has demonstrated a surprising degree of resilience. While domestic American industries, consumers, and international exporters grapple with elevated costs, global commerce has adapted, finding alternative routes and markets. Concurrently, a mounting tide of domestic public and corporate opposition to the administration’s tariff regime suggests that the political tolerance for unabated protectionism may finally be reaching its limits, potentially paving the way for a future retreat from aggressive trade barriers.
Main Facts and the Current Landscape
The cornerstone of the administration’s current economic strategy is a series of universal and targeted levies imposed on a vast array of imported goods. Unlike traditional trade policy, which typically relies on deliberate legislative action or formal dispute resolution mechanisms, the current approach has been characterized by volatility. Duties are frequently raised, lowered, or recalibrated for specific products and nations with little advance notice, generating profound uncertainty for supply chain managers, corporate financial planners, and foreign governments alike.
Data compiled through late 2026 indicates that these measures have fundamentally failed to achieve their primary stated objectives. Rather than narrowing the persistent US trade deficit, the aggregate trade gap has remained stubbornly wide, driven by resilient domestic consumer demand and structural economic factors. Furthermore, the promise of a manufacturing renaissance fueled by import protection has largely failed to materialize. Instead of adding jobs on factory floors, businesses across the manufacturing spectrum report that higher input costs for raw materials such as steel, aluminum, and intermediate components have squeezed profit margins, forced workforce reductions, or compelled companies to pass higher prices directly onto American households.
Historical Context and Chronology of the Second-Term Trade Shift
To understand the scope of the current economic environment, it is necessary to examine the trajectory of US trade policy over the past decade. During his first term (2017–2021), President Trump broke with decades of bipartisan consensus by initiating trade conflicts, most notably with the People’s Republic of China, and renegotiating core agreements like NAFTA into the United States-Mexico-Canada Agreement (USMCA). However, those initial measures—while disruptive—were often constrained by institutional norms, internal administration debates, and the lingering influence of traditional free-market advisers.
Upon securing a second term, the administration encountered fewer internal checks, enabling a much more aggressive and unhindered execution of trade nationalism.
- January 2025: Following inauguration, the administration immediately issues executive orders initiating sweeping reviews of all major bilateral trade deficits and signaling the deployment of emergency economic powers to bypass traditional legislative hurdles.
- Spring 2025: Broad baseline tariffs are announced on imports from major trading partners across Asia, Europe, and the Americas. The administration dismisses concerns regarding retaliatory measures, framing the duties as an essential tool for national security and economic independence.
- Late 2025: As individual exemptions are granted, revoked, or modified based on ad-hoc negotiations, business uncertainty peaks. Multinational corporations report significant delays at ports of entry and soaring logistical expenses.
- Mid-2026: Economic indicators confirm that while import prices have spiked, manufacturing employment figures remain largely stagnant. Public opinion polls begin to register a significant shift, with a growing majority of voters expressing concern over the cost of living and inflation directly linked to import taxes.
- Late 2026: Mounting pressure from business coalitions, agricultural exporters, and retail associations leads to initial bipartisan discussions in Congress regarding legislative checks on executive tariff authority.
Supporting Data and Economic Realities
The economic toll of the second-term tariff agenda is increasingly documented through empirical research from academic institutions, international organizations, and domestic think tanks. According to recent trade metrics, the effective US tariff rate on all imported goods has climbed past levels unseen in nearly a century.
When the Smoot-Hawley Tariff Act was passed in 1930, it triggered a destructive spiral of retaliatory protectionism that deepened the global economic downturn. While the modern global economy has thus far avoided a total collapse of trade, the similarities in unilateral escalation are striking. Studies tracking consumer price indices indicate that American households are absorbing the bulk of the tariff burden through higher costs for automobiles, electronics, apparel, and home goods.
Conversely, the promised influx of capital investment into domestic manufacturing has been muted. While a handful of high-profile facilities have broken ground—often heavily subsidized by separate industrial policy legislation like the CHIPS Act or the Inflation Reduction Act—the broader manufacturing sector reports net stagnation. Industry analysts point out that modern supply chains are deeply integrated; penalizing imported inputs often makes US-assembled finished goods less competitive on the global stage, counteracting the intended protective effect.
Official Responses and Stakeholder Reactions
The administration has consistently defended its trade policies as a necessary defense of American workers against unfair foreign competition and currency manipulation. Administration officials maintain that the threat and application of tariffs serve as a powerful leverage tool to compel foreign actors to negotiate more favorable terms of trade and to bring industrial production back to domestic soil. In public briefings, trade representatives argue that short-term price adjustments are a small price to pay for long-term economic sovereignty and industrial resilience.
However, the response from the broader business community, agricultural sectors, and international allies has grown increasingly critical.
Major business associations, representing retailers, importers, and logistics providers, have intensified lobbying efforts in Washington, warning that prolonged tariff instability threatens economic growth. Agricultural exporters—frequently the primary target of retaliatory tariffs enacted by trading partners such as the European Union, China, and several Latin American nations—have expressed deep frustration over lost market share in vital overseas agricultural markets.
International reactions have evolved from initial shock during the first term to a more calculated management strategy in the second. Rather than engaging in all-out trade wars that could destabilize global markets further, many major economies have pursued a dual track: filing formal challenges through the restructured mechanisms of the World Trade Organization (WTO) while simultaneously diversifying their export destinations away from the United States to reduce long-term vulnerability.
Broader Impact and Future Implications
The unfolding reality of the post-2025 trade environment offers critical lessons regarding the limits of protectionism in a deeply interconnected global economy. While the Trump administration has successfully disrupted traditional trade flows and forced a recalibration of international supply chains, the anticipated domestic benefits—namely, a resurgence of blue-collar manufacturing employment and a reduction in trade imbalances—have failed to materialize as promised.
Yet, the most significant long-term consequence of this era may not be the tariffs themselves, but the reaction they have provoked. The sheer unpredictability and economic friction generated by the administration’s policies have galvanized a broad-based political and economic coalition against protectionism. Consumer weariness with persistent inflation, coupled with mounting corporate pushback against supply chain instability, is steadily altering the domestic political landscape.
As public opposition solidifies, the political cost of maintaining high tariff walls is projected to rise significantly. This growing resistance could serve as the catalyst for a future legislative and executive retreat from extreme protectionism, clearing the path toward a restoration of rules-based, multilateral trade engagement. Whether that pivot occurs through a shift in administration priorities or through congressional reassertion of its constitutional authority over commerce, the events of the past two years have highlighted both the disruptive power of unilateral trade policy and the remarkable durability of global economic integration.