Gold Prices Suffer Sharp Correction After Record January Rally Driven by Monetary Shifts and Regulatory Interventions

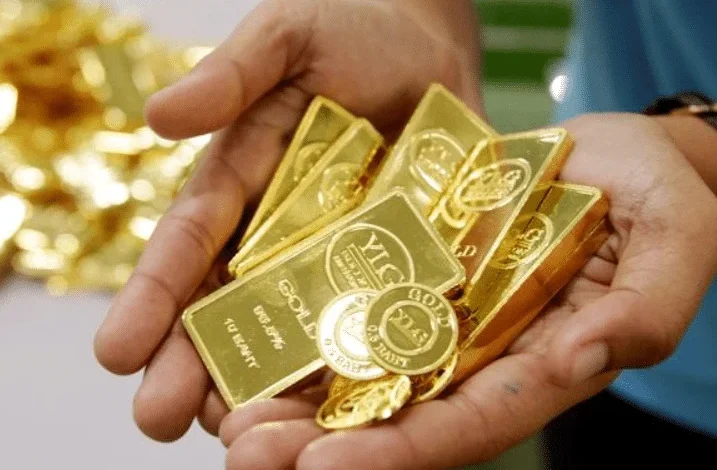
The global gold market is currently undergoing a severe and rapid correction phase, erasing a significant portion of the stellar gains accumulated during an aggressive price rally earlier in January. This sudden downturn has caught many market participants off guard, shifting the narrative from unbridled optimism to cautious risk management. The ongoing market adjustment is not an isolated event; rather, it is the culmination of shifting macroeconomic expectations, forced algorithmic deleveraging across major exchanges, and proactive regulatory clampdowns in pivotal Asian trading hubs. While the underlying fundamentals supporting the precious metal remain structurally sound, the sheer velocity of the recent pullback underscores how overextended and vulnerable speculative positioning had become following months of emotionally driven buying.
Chronology of the January Rally and Sudden Reversal
The genesis of the current gold market dynamics traces back to the opening weeks of January, when precious metals experienced a historic upward surge. Investors rushed into bullion, driven by a cocktail of geopolitical anxieties, expectations of aggressive monetary easing by the United States Federal Reserve, and relentless momentum buying. Throughout this period, technical indicators consistently flashed overbought signals, yet market participants largely ignored these warnings, fueled by the psychological momentum of breaking successive price milestones.
The turning point materialized in the final week of January, triggered by a profound shift in US monetary policy expectations. Markets began pricing in a more hawkish trajectory following key political and economic appointments, notably the nomination of Kevin Warsh as the next Federal Reserve Chair. Unlike his perceived predecessors, Warsh’s track record and public commentary suggested a staunch defense against inflation and a reluctance to implement aggressive rate cuts. This sentiment was further compounded by stubbornly high US producer inflation data, which fortified the US dollar and drove real Treasury yields higher. Because gold is a non-yielding asset, the sudden resurgence of the greenback and climbing yields dealt a heavy blow to the commodity, sparking the initial wave of long liquidation.
As key moving averages were decisively breached, systematic trading algorithms and quantitative funds stepped in to execute pre-programmed stop-loss orders. This forced deleveraging accelerated the downward momentum, turning a routine technical correction into a steep, liquidity-driven drop that caught retail and institutional investors alike in a cascade of margin calls.
Regulatory Crackdowns and Asian Market Interventions
The vulnerabilities exposed by the US monetary shift were further amplified by dramatic policy interventions in key Asian markets, most notably China. Recognizing the speculative frenzy gripping domestic retail and institutional investors, major state-owned financial institutions took unprecedented steps to cool the market. The Industrial and Commercial Bank of China (ICBC), the Bank of China, and the China Construction Bank issued public warnings to precious metals investors, explicitly characterizing the current market environment as "technically fragile" and urging extreme caution against blind speculation.
In tandem with these verbal warnings, the Shanghai Gold Exchange (SGE) took direct regulatory action. The exchange altered its margin requirements and price limits, making aggressive leveraged speculation significantly more expensive and difficult to maintain. Chinese regulatory bodies have grown increasingly concerned that the exponential growth in gold prices was being fueled by speculative debt and emotional sentiment rather than sustainable end-user industrial or physical jewelry demand. By reining in excessive leverage, Beijing effectively defused a potential asset bubble, though the immediate side effect was a localized shockwave that rippled through global pricing mechanisms.
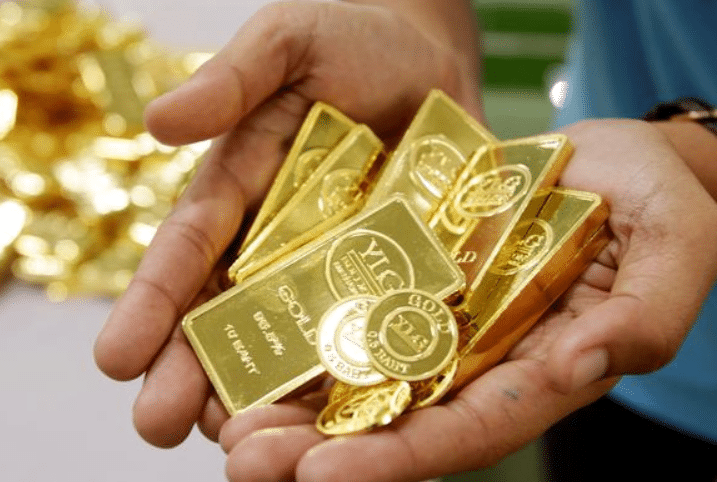
The shockwaves were not confined to institutional trading desks in major financial centers; they quickly trickled down to retail participants in smaller frontier economies. In Kyrgyzstan, for instance, reports emerged of citizens rushing to state-owned bullion distributor Kyrgyzaltyn to liquidate certified gold bars. This frantic rush to sell highlighted a classic behavioral tipping point: as soon as global prices experienced a significant slump, retail sentiment pivoted almost overnight from hoarding as a hedge against inflation to desperate capital preservation.
Macroeconomic Resilience and Long-Term Fundamentals
Despite the severity of the ongoing technical correction, financial analysts and market strategists emphasize that the core structural pillars supporting the gold market remain entirely intact. The primary driver of institutional demand over the past several years—sustained central bank gold accumulation—shows no signs of abating. Emerging market central banks continue to aggressively diversify their foreign exchange reserves away from fiat currencies, using market dips as strategic opportunities to acquire physical bullion at more attractive valuations.
On the geopolitical front, systemic risks continue to simmer. While immediate rhetoric surrounding tensions between the United States and Iran has experienced brief periods of cooling, the underlying geopolitical architecture remains fraught with friction. Ongoing conflicts in Eastern Europe and the Middle East, coupled with persistent trade fragmentation and sovereign debt concerns among Western economies, ensure that gold’s traditional role as the ultimate safe-haven asset remains relevant.
Consequently, market veterans view the current downturn not as a structural trend reversal signaling a permanent bear market, but rather as a much-needed, albeit painful, market reset. For gold to resume its previous upward trajectory and challenge historical highs, analysts argue that the market will likely require renewed macroeconomic stress, escalating geopolitical friction, or a definitive, dovish pivot in global central bank monetary policies.
Technical Analysis: Navigating the 200-Period Moving Average Breakdown
From a technical standpoint, the market outlook in the intermediate timeframe remains challenging. On the 4-hour chart, gold prices have decisively breached the critical 200-period moving average, hovering near the $4,600 threshold for the first time since November 2025. This decisive break beneath such a closely monitored institutional benchmark signals a shift in market structure, indicating that a sustained short-term downtrend is currently in play and opening the door to potential extended losses.
[Key Technical Levels Summary]
- Immediate Resistance (20-period MA): $5,250
- Psychological Milestone: $5,000
- Intermediate Resistance (100-period MA): $4,835
- Critical Breakdown Level (200-period MA): $4,600
- Intraday Support Floor: $4,400
- Gap Fill Target: $4,330
- Major Psychological Support: $4,000
Despite the dismal near-term price action, technical indicators also point toward extreme exhaustion among sellers. The Relative Strength Index (RSI) on the 4-hour timeframe has dipped firmly into oversold territory. This technical condition frequently precedes a period of market consolidation, where prices stabilize and form a base before determining their next directional breakout.
If the market attempts a recovery rally, bulls will first need to reclaim the 100-period moving average situated near $4,835. Beyond that, the psychological $5,000 mark stands as a formidable barrier, followed closely by the 20-period moving average at $5,250, which would need to be breached to invalidate the current bearish bias.
Conversely, if selling pressure persists, gold prices risk testing today’s intraday lows around $4,400. A failure to hold this local floor could trigger a swift move to fill an existing chart gap down at $4,330. In a worst-case liquidation scenario where macroeconomic headwinds intensify further, the broader market could eventually test the major psychological support level at $4,000.
As the market navigates this high-volatility environment, institutional investors and retail traders alike are advised to monitor central bank communications, upcoming US employment and inflation prints, and regulatory updates from major Asian commodity exchanges to gauge the timing of the next definitive market move.
Related posts: