The Artificial Intelligence Debt Time Bomb Threatening Global Financial Stability

LONDON — Anyone who lived through the internet boom and bust of the late 1990s and early 2000s should find the current AI investment cycle worryingly familiar. Heavy reliance on debt means that if investors decide to stop lending into the boom, a financial crisis will be inevitable—and far worse than the subprime-mortgage crisis in 2008. It is a truth universally acknowledged that transformative new technologies rewrite the rules of finance. Or so we are told in numerous commentaries, social-media posts, and regulatory filings relating to the current artificial intelligence investment boom, which financial analysts increasingly warn may well prove to be an unsustainable market bubble.
As capital continues to pour into large language models, specialized semiconductor manufacturing, and massive data center infrastructure at an unprecedented pace, economists, regulators, and industry observers are drawing parallels to historical market crashes. The fundamental concern centers not merely on lofty equity valuations, but on the intricate, highly leveraged debt structures financing the foundational layers of the generative AI revolution.
The Anatomy of the AI Infrastructure Boom
The current expansion phase of artificial intelligence is characterized by capital expenditures that dwarf previous technological epochs. Unlike the early internet era, which was largely driven by venture capital equity and retail stock speculation, the contemporary AI boom relies heavily on corporate debt, private credit markets, and complex vendor-financing arrangements.
Major technology conglomerates, specialized cloud providers, and venture-backed startups are borrowing staggering sums to secure scarce graphics processing units (GPUs), construct high-density data centers, and lock in multi-year energy supply contracts. These capital-intensive requirements have turned traditional software development into a heavy-industry enterprise. Because the hardware depreciates rapidly and software monetization models are still evolving, lenders are taking on unprecedented structural risk.
Market analysts note that the race to achieve artificial general intelligence (AGI) has created a prisoners’ dilemma among major technology firms. Companies feel compelled to over-invest in computing power simply to remain competitive, leading to a surge in corporate borrowing even as interest rates remain elevated compared to the ultra-low rate environment of the previous decade.
A Chronology of the Modern Tech Bubble
To understand the trajectory of the current market, financial historians look back at the compounding cycles of technological innovation and overextension over the past three decades.
The late 1990s marked the dot-com boom, characterized by soaring equity valuations for internet startup companies with little to no revenue. When the Nasdaq peaked in March 2000 and subsequently crashed, trillions of dollars in market value evaporated, though the broader banking system absorbed the blow because debt leverage was relatively contained compared to the housing sector.
Less than a decade later, the 2007–2008 global financial crisis demonstrated the destructive power of systemic leverage. Driven by subprime mortgages bundled into complex collateralized debt obligations (CDOs), the collapse revealed how hidden debt concentrations could freeze interbank lending and trigger a worldwide economic contraction.
By the early 2020s, post-pandemic monetary easing fueled a new wave of speculative investments in cryptocurrency, special purpose acquisition companies (SPACs), and early-stage tech. As central banks pivoted to aggressive monetary tightening in 2022 to combat inflation, many of these speculative assets underwent sharp corrections.
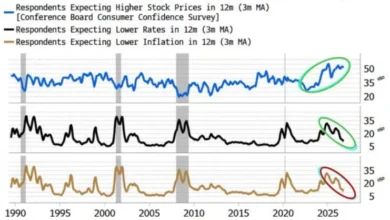
However, the launch of advanced generative AI models in late 2022 catalyzed a massive redirection of global capital. By 2024 and 2025, AI infrastructure spending had become the primary driver of capital markets, pushing a handful of mega-cap technology stocks to historic valuation peaks while debt issuance for data center expansion surged to record highs. By late 2026, concerns over the return on investment (ROI) for these multi-billion-dollar clusters reached a boiling point among institutional lenders.
Supporting Data and Financial Exposure
The scale of capital deployment in artificial intelligence defies traditional economic benchmarks. According to recent market intelligence reports, global capital expenditure on AI-related data centers, networking hardware, and specialized power generation is projected to exceed hundreds of billions of dollars annually.
A significant portion of this spending is debt-financed. Private credit funds, which have expanded rapidly in recent years to fill the void left by traditional commercial banks pulling back from riskier corporate lending, have become deeply exposed to tech infrastructure projects. These private market instruments often lack the transparency of public debt, making it difficult for regulators to gauge the true extent of systemic leverage.
Furthermore, semiconductor supply chains are tied to exceptionally high fixed costs. A single advanced fabrication facility costs upwards of $20 billion to construct, requiring guaranteed long-term demand to service the underlying debt. If enterprise adoption of generative AI plateaus or fails to generate sufficient revenue to offset these capital expenditures, borrowers may face severe liquidity crunches.
Industry Responses and Regulatory Warnings
As the debt burden accumulates, financial watchdogs and industry leaders have begun sounding alarms. Central bank officials in major jurisdictions have issued cautionary statements regarding the interconnectedness of private credit markets and technology infrastructure financing.
Regulatory bodies are scrutinizing the valuation models used by private equity and venture capital firms to justify continuous fundraising rounds. Critics argue that circular investments—where major cloud providers invest in AI startups that, in turn, spend those funds renting cloud capacity from the same providers—artificially inflate demand metrics and mask underlying financial fragility.
Conversely, proponents of the current investment cycle defend the spending spree as a necessary capital mobilization for a paradigm-shifting technology. Industry executives argue that the productivity gains promised by artificial intelligence across healthcare, logistics, scientific research, and software engineering will ultimately justify the upfront costs. They contend that comparing the current AI expansion to the 2000 dot-com bubble ignores the robust balance sheets and massive cash reserves held by the primary market leaders.
Broader Economic Implications and Systemic Risks
The primary risk identified by economists is not merely a decline in technology equity prices, but a credit event cascading through the broader financial system. If high-yield corporate borrowers and specialized infrastructure providers default on their debt obligations, the shockwaves would be felt far beyond Silicon Valley and Wall Street.
Pension funds, insurance companies, and institutional asset managers heavily invested in private credit and corporate bonds could face significant write-downs. A sudden reassessment of risk by lenders would trigger a liquidity squeeze, halting credit creation across other sectors of the economy. Because modern financial markets are deeply interconnected through derivatives, automated trading algorithms, and cross-border lending facilities, a contraction in tech sector credit could precipitate a broad economic downturn.
Preventing such a scenario requires proactive risk management from both financial institutions and regulatory authorities. Ensuring transparency in private credit markets, enforcing strict leverage limits, and maintaining realistic revenue expectations for enterprise AI adoption will be critical in determining whether the technology fulfills its transformative promise without destabilizing the global economy.