Quantitative Analysis of SEC Form 4 Insider Purchases Reveals Short-Term Market Associations Without Long-Term Alpha Persistence

Form 4 filings serve as one of the most accessible yet frequently misunderstood datasets in quantitative finance. Because they are public, structured, and governed by a strict regulatory mandate requiring reporting within two business days of a transaction, they appear to offer a "gold mine" for predictive modeling. However, a rigorous event study covering the period from January 1, 2022, through June 30, 2026, reveals that the reality of insider trading signals is significantly more nuanced than the simplistic "insider-buys-stock-so-you-should-too" narrative. By processing over 1.3 million non-derivative transaction rows, researchers have parsed the signal from the noise, finding that while insider purchases are associated with immediate short-term price appreciation, the evidence for long-term alpha persistence remains elusive.
The Mechanics of Regulatory Disclosure
To understand the impact of these signals, one must first understand the anatomy of a Form 4. Section 16 of the Securities Exchange Act of 1934 mandates that officers, directors, and beneficial owners of more than 10% of a registered equity class report changes in their ownership. The SEC’s structured data sets—specifically the NONDERIV_TRANS.tsv and SUBMISSION.tsv files—provide the raw material for this analysis.
The study in question applied a rigorous filtering funnel, starting with 1,345,036 raw transaction rows and narrowing the focus to 11,957 component events. This process involved excluding derivative trades, gifts, and transactions that failed to meet price-validation standards. Crucially, the study also excluded joint filings, which are a notorious trap for quantitative analysts; because the SEC’s research tables do not always link specific transactions to a unique reporting owner in multi-owner filings, researchers often double-count or misattribute trades. By isolating single-owner filings and filtering for C-suite roles (CEO, CFO, and COO), the study established a cleaner, though smaller, sample of 7,406 unique issuer-day signals.
Chronology and the Timing of Information
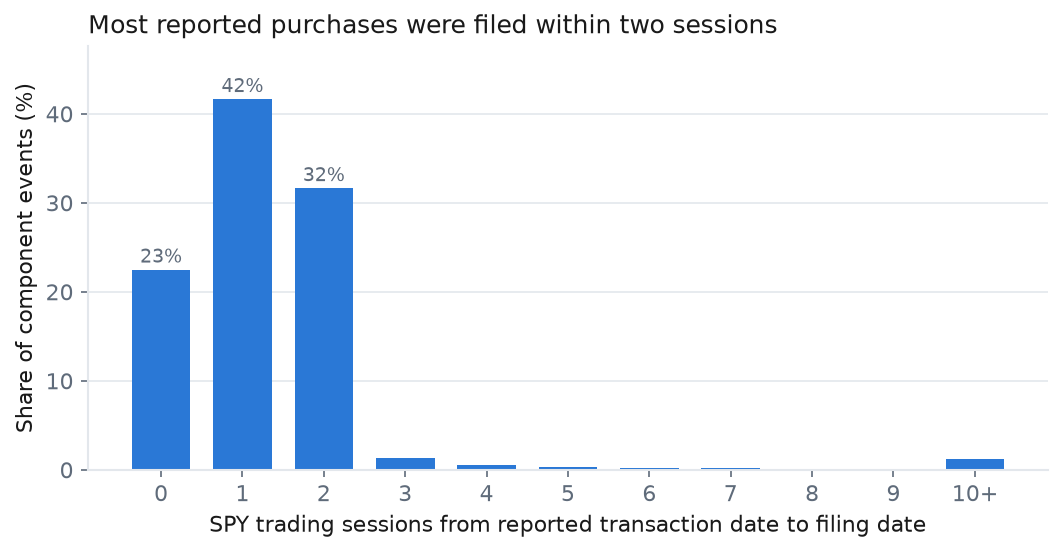
The timing of these disclosures is critical. Under SEC rules, insiders must file by the end of the second business day following a reportable transaction. This lag means that the transaction date itself is not actionable information for an outside investor; it is historical data. Consequently, the study utilized a filing-date event study design, where the entry point is the first SPY trading session strictly after the filing date.
Figure 1 of the analysis, which tracks filing latency, confirms that the vast majority of insiders adhere to the two-day deadline, with a median lag of just one trading session. This high level of compliance reinforces the utility of the filing date as the true starting point for market reaction. By ignoring the transaction date, the study avoids the common "lookahead bias" that has plagued earlier academic literature, where researchers incorrectly assumed that market prices moved in response to a trade that had not yet been disclosed to the public.
Statistical Findings: Short-Term Gains vs. Long-Term Uncertainty
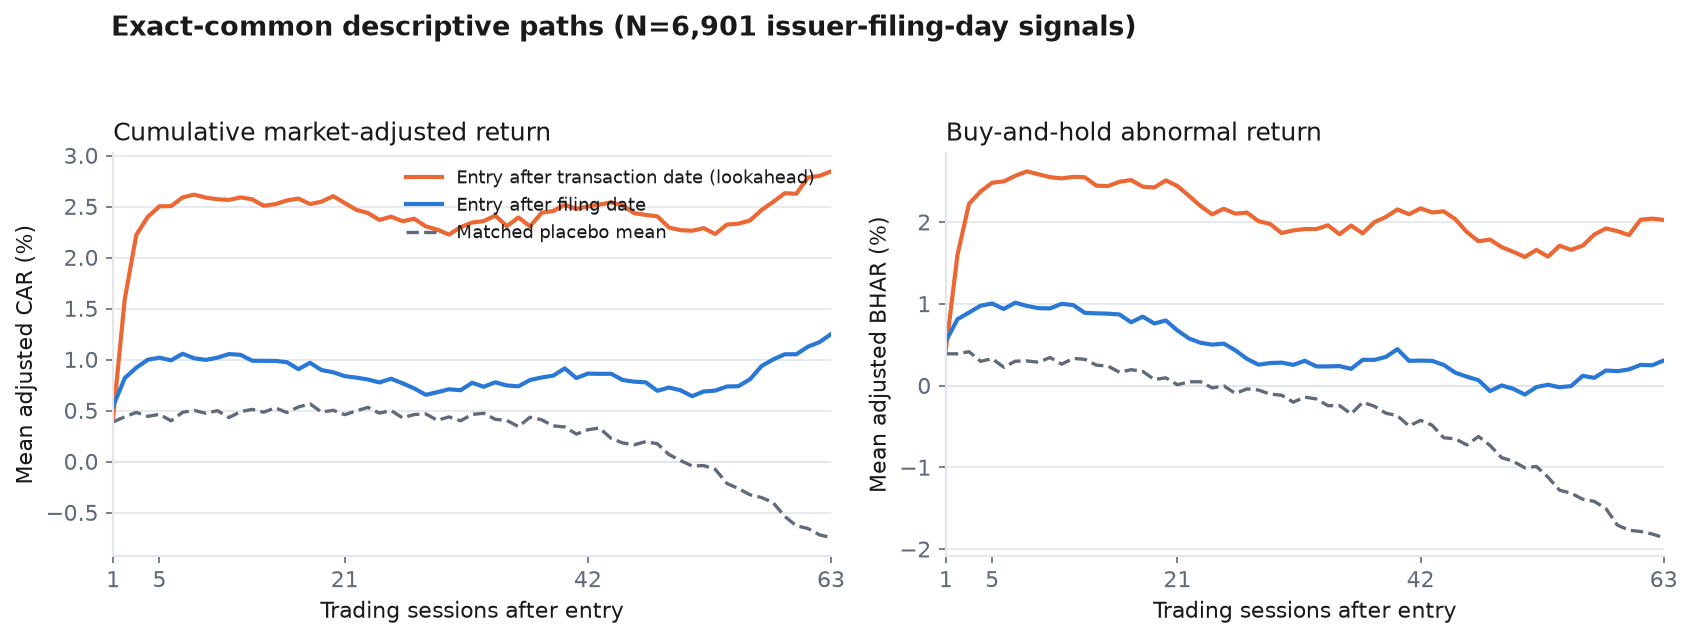
The headline results are intentionally modest. For the next session following a filing, the SPY-adjusted mean cumulative abnormal return (CAR) is +0.534%. Over a five-session window, this increases to +1.009%. These figures are statistically significant, with two-way clustered t-statistics of 6.460 and 5.053, respectively. However, the narrative changes significantly as the time horizon extends.
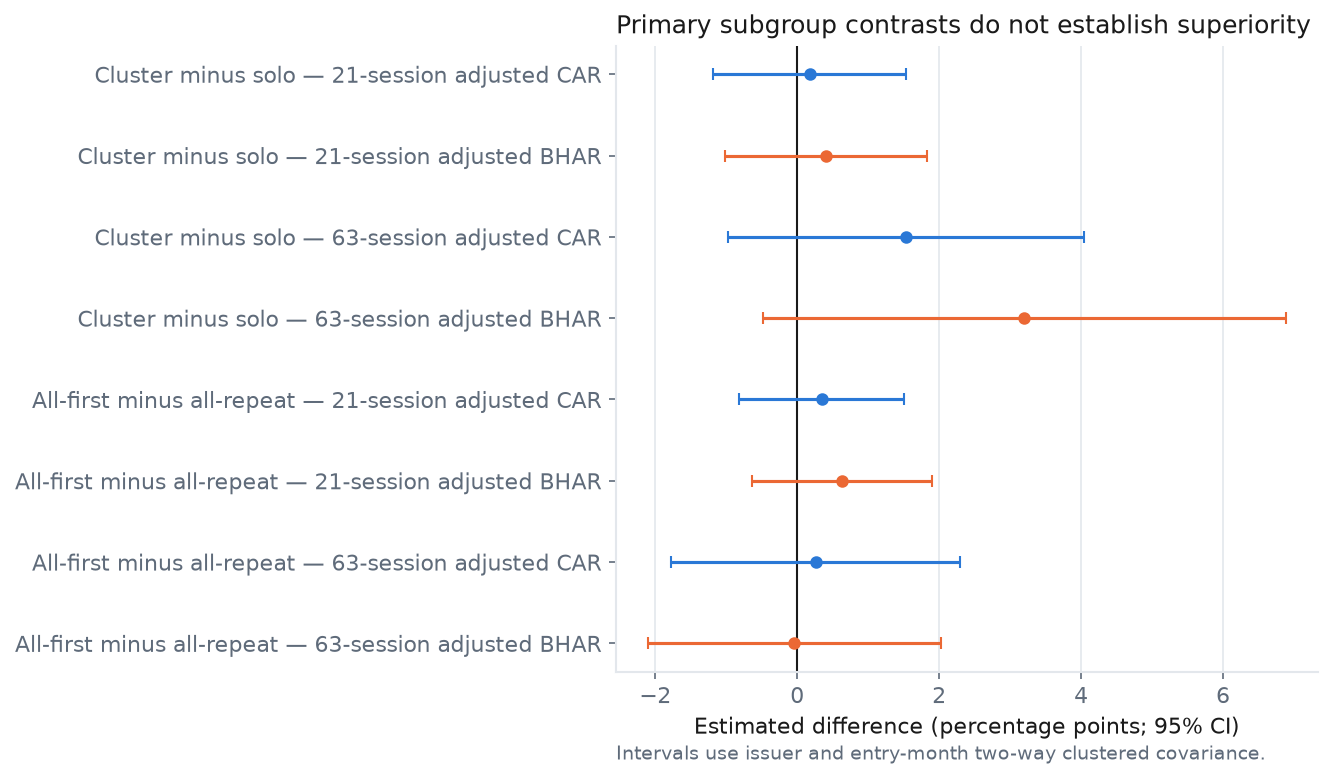
At 21 and 63 sessions, the adjusted CAR confidence intervals widen to include zero. Similarly, the buy-and-hold abnormal return (BHAR) data—a more accurate measure of long-term investor experience—shows no persistent outperformance. At 63 sessions, the 1%-winsorized mean BHAR is actually negative, and the median is -3.605%. This suggests that while there is an initial, reflexive market reaction to an insider purchase, this reaction is not a precursor to a sustained, long-term trend.
The Role of Market Models and Sensitivity
The study also highlights the danger of relying on complex market models. When applying a market-model sensitivity analysis, the results appear much more favorable, showing a +6.560% return at 63 sessions. However, the researcher notes that this is likely an artifact of negative pre-event alpha in the stocks chosen by insiders. Because many insiders buy stocks that have been underperforming, the "market model" expects further underperformance. When the stock merely performs in line with the market, the model registers a positive residual, which compounds over time. This illustrates why simple adjusted returns are often more reliable than complex model-based projections: they avoid the "mechanical" lifting of returns that can occur when dealing with distressed or falling assets.
Comparison with Previous Academic Literature
The findings align with, yet refine, the foundational work of scholars like Lakonishok and Lee (2001) and Cohen, Malloy, and Pomorski (2012). While earlier studies established that insider purchases are generally more informative than sales, the current research emphasizes that not all "Code-P" transactions are "opportunistic." By removing transactions affirmatively flagged as Rule 10b5-1 plan trades—which are pre-scheduled and automated—the study attempted to isolate discretionary trading. Yet, even within this "non-10b5-1" group, the results suggest that the market effectively prices in the information within the first week of disclosure.
Implications for Investors and Data Analysts
The primary takeaway for the investment community is one of caution regarding liquidity and capacity. For many of the signals identified, the aggregate insider purchase value represents a significant percentage of the average daily volume. If an investor were to attempt to replicate these trades, they would likely face substantial market impact and execution costs that are not reflected in these academic averages.
Furthermore, the study serves as a masterclass in data hygiene. By documenting the "funnel" of excluded data, the researcher demonstrates how easily quantitative studies can be biased by "survivorship-free" assumptions or the failure to account for corporate actions like stock splits or delistings. The use of two-way clustering—accounting for both the issuer and the calendar month—is a rigorous standard that many retail-level backtests fail to meet.
Conclusion: A Call for Methodological Rigor
The evidence presented suggests that while SEC Form 4 filings remain a vital source of market data, they do not provide a "magic bullet" for long-term alpha. The observable price action is concentrated in the immediate aftermath of a filing, likely reflecting a rapid adjustment by the market to the perceived confidence of the insider.
For those building quantitative strategies, the lesson is clear: focus on the filing date, treat transaction-level data with extreme skepticism, and be wary of long-horizon projections that rely on fitted market models. The true value of this data lies not in the hope of finding a "beating the market" strategy, but in the ability to understand the information flow within modern capital markets. As the industry moves toward more sophisticated, automated analysis of alternative data, the methods outlined here—preserving timestamps, cleaning for corporate actions, and using robust clustering—will become the baseline for any credible research.
Ultimately, this study reinforces the necessity of skepticism in financial data science. When a dataset is as public and as heavily analyzed as Form 4 filings, the "low-hanging fruit" has long been picked. What remains are the complexities of market microstructure and the reality that information, once public, is rarely a source of prolonged competitive advantage. The findings confirm that while insiders may have a unique perspective on their firms, the market is highly efficient at incorporating that perspective into prices within a matter of days, leaving little room for the average participant to capture significant, sustained value from the disclosure alone.