The Paradox of Tax Efficiency and the Hidden Costs of Wealth Optimization

Taxes remain one of the most contentious elements of modern financial management, serving as a psychological trigger that often overrides rational economic decision-making. While the fundamental goal of any investment strategy is to maximize capital appreciation, the act of settling tax liabilities on those gains frequently feels like a personal loss. This phenomenon, rooted in the behavioral economic concept of loss aversion, creates a complex dynamic for high-net-worth individuals: the very success of their portfolio—represented by substantial taxable gains—becomes a barrier to the liquidity and diversification necessary to protect their long-term wealth.
The Anatomy of Tax-Induced Inertia
The accumulation of wealth through concentrated positions, particularly in the technology sector, has reached a historical peak in the mid-2020s. Many investors who entered the market during the previous decade now find themselves holding massive unrealized gains in individual securities. Financial advisors frequently encounter a recurring dilemma: the prudent advice to diversify a portfolio is met with significant resistance because the act of rebalancing would trigger immediate capital gains taxes.
This behavior reflects a widespread misconception regarding the nature of tax payments. In a healthy market environment, a tax bill is fundamentally a "success tax." It signifies that an asset has appreciated, providing the investor with profit even after the government’s share is extracted. However, for many, the sting of the tax payment outweighs the utility of the remaining profit, leading to a state of financial paralysis. This inertia prevents investors from mitigating the risks of concentration, leaving them vulnerable to market volatility that could erode the very gains they are attempting to protect.
The Evolution of Tax-Aware Investment Technology
The financial industry has responded to this paralysis with increasingly sophisticated technological solutions designed to minimize tax friction. Historically, investors had few options beyond "buy and hold" strategies. Today, the landscape has shifted toward algorithmic, data-driven approaches that turn tax management into a competitive advantage, often referred to as "Tax Alpha."
Direct indexing emerged as the first major step in this evolution. By purchasing the individual securities that comprise an index rather than a fund, investors gain the ability to conduct tax-loss harvesting on a security-by-security basis. This allows a portfolio to systematically sell underperforming assets to offset gains, thereby lowering the effective tax rate.
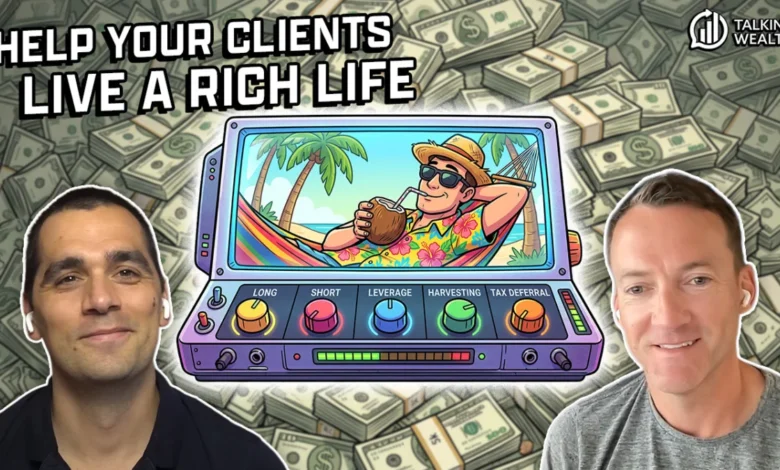
However, direct indexing faces limitations when an investor holds a portfolio with extreme concentration or when the goal is to liquidate positions rapidly. To address these gaps, the industry has introduced long/short direct indexing. By incorporating a margin-based, long/short strategy, these portfolios gain the flexibility to create losses at an accelerated pace. By shorting specific stocks or indices, investors can generate tax-deductible losses that offset the gains realized from rebalancing concentrated long positions. While this approach introduces higher complexity and potential costs, it provides a powerful mechanism for managing tax liabilities in ways that were previously inaccessible to retail or private wealth clients.
The Behavioral Implications of Deferral
While the mathematical benefits of tax-aware investing are clear, the psychological implications are profound. Financial theorists and wealth management professionals have begun to observe a troubling side effect of these high-efficiency strategies: the "lock-in effect."
When an investor successfully utilizes complex tax deferral strategies, they often become even more reluctant to sell their assets. Because the strategy effectively pushes the tax liability into the future, the buildup of unrealized gains continues to grow. Over time, the size of the potential tax bill compounds, making the investor feel as though they are perpetually "trapped" in the strategy. This phenomenon, sometimes described as "living rich to die poor," results in individuals who possess significant wealth on paper but find themselves unable or unwilling to spend it during their lifetimes due to the looming specter of tax realization.
Data suggests that as portfolios age and markets drift upward, the ability to harvest losses decreases. If a strategy relies heavily on generating losses to offset gains, a prolonged bull market can leave the investor with few levers to pull. Consequently, the investor finds themselves with a highly appreciated, illiquid portfolio that is difficult to unwind without incurring a massive, multi-year tax penalty.
Strategic Trade-offs and Financial Planning
The adoption of long/short direct indexing and other aggressive tax-deferral methods requires a nuanced assessment of the investor’s specific goals. The most significant trade-off is between the maximization of net-of-tax wealth and the actual utility of the capital. Financial planners are increasingly emphasizing that the purpose of wealth is consumption and security, not merely the optimization of an account statement.
Research indicates that there is a "point of diminishing returns" regarding tax optimization. When the complexity of a strategy begins to dictate the investor’s lifestyle—or when it forces them to hold concentrated positions that do not align with their risk tolerance—the strategy has likely become counterproductive. The primary challenge for modern investors is to distinguish between "tax alpha" that supports a broader financial plan and "tax optimization" that serves as an end in itself, potentially hindering an investor’s ability to live comfortably or diversify their risk.
Expert Perspectives on Implementation
The decision to utilize sophisticated tax-aware strategies should be viewed through a situational lens rather than a universal one. Experts in the field argue that the best strategy is one that aligns with the investor’s life stage, liquidity needs, and risk appetite.
- Early Stage: Investors with high income and low accumulated gains may benefit from simple direct indexing to build a tax-efficient base.
- Growth Stage: Investors with significant concentrated gains in single stocks may require more advanced techniques, such as long/short direct indexing, to transition into a diversified portfolio.
- Distribution Stage: Investors nearing retirement must prioritize liquidity over further tax deferral. At this stage, paying some taxes to simplify the portfolio and reduce risk is often a superior strategy to deferring taxes at the cost of excessive volatility.
The consensus among wealth managers is that taxes should be a factor in, but not the driver of, investment decisions. The "best" strategy is one that maintains the integrity of the portfolio’s risk profile while keeping the tax burden manageable, without allowing the fear of a tax bill to dictate the investor’s life choices.
Conclusion: A Holistic View of Wealth
As the financial industry moves toward an era of hyper-customization, the tools available to manage tax liabilities will continue to evolve. However, the fundamental human tendency toward loss aversion will remain a constant variable. Investors must balance the mathematical benefits of tax deferral against the reality of their own psychological constraints.
Ultimately, financial planning is a delicate exercise in managing trade-offs. While paying taxes is never an enjoyable experience, it is a byproduct of economic growth. By focusing on the broader objective—ensuring that wealth provides the desired quality of life—investors can navigate the complexities of tax management without falling into the trap of over-optimization. The goal is to build a portfolio that serves the investor, not a strategy that forces the investor to serve the portfolio. Moving forward, the most successful investors will be those who can discern when to leverage technology to reduce their tax burden, and when to accept a tax bill as the necessary cost of a successful and well-managed financial life.
Related posts: