N26 Unveils Aura: A €55-Per-Month Ceramic Card and Lifestyle Super-App Play in Germany

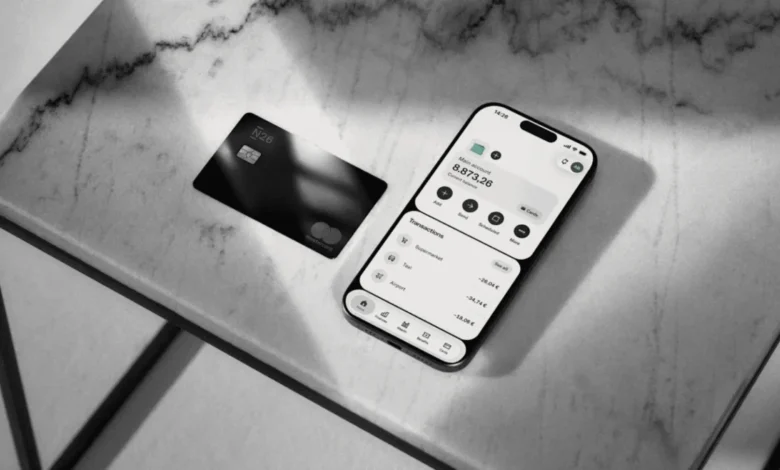
Berlin-headquartered digital banking giant N26 has officially launched its most exclusive banking tier to date, introducing a high-end account named Aura. Priced at €55 per month, the new offering represents a massive leap forward for the neobank, positioning it firmly in the luxury financial lifestyle segment. Until the debut of Aura, N26’s personal product lineup consisted of four distinct tiers: Standard, Smart, Go, and Metal. Aura now sits comfortably at the top of this hierarchy as the fifth and most expensive option, more than tripling the monthly cost of the Metal tier while drastically expanding the breadth of lifestyle, investment, and travel benefits bundled into the account.
The launch underscores a broader, long-term strategic evolution for the company. Rather than functioning purely as a traditional digital checking account provider, N26 is actively transforming into a fully integrated financial platform. By combining high-end banking services with a curated suite of everyday subscriptions and investment perks, the neobank is testing the boundaries of consumer willingness to pay for premium financial ecosystems. Initially, Aura is rolling out exclusively in Germany for eligible personal and business account holders, marking a deliberate, targeted debut before any potential broader European expansion.
The Anatomy of N26 Aura: Pricing and Luxury Perks
At €55 per month, N26 Aura is engineered to attract high-earning professionals, frequent travelers, and digital natives who already spend significant sums on premium software, entertainment, and lifestyle subscriptions. Departing from the traditional plastic or stainless steel cards favored by modern neobanks, Aura ships with an exclusive, ceramic mirror-finish payment card designed to signal status and exclusivity.
Beyond its aesthetic appeal, the account justifies its steep price tag through a dense matrix of features. Aura cardholders receive unlimited, complimentary airport lounge access worldwide, shielding travelers from the friction of flight delays and layovers. For retail investors and wealth-builders, the account includes up to 15 free trades per month, significantly lowering the barrier to active market participation.
Perhaps the most commercially astute element of the Aura tier is its heavy integration of third-party lifestyle subscriptions. N26 has bundled services that consumers frequently purchase independently, including Amazon Prime, Google AI Pro, and NordVPN, among other lifestyle offerings. By absorbing these costs into the monthly subscription fee, N26 aims to position Aura not as an expensive banking fee, but as a consolidated digital utility bill that pays for itself for power users.
Strategic Competition and the Rise of the Financial Super-App
The introduction of Aura brings N26 into direct, head-to-head competition with its chief European rival, Revolut. Revolut currently offers its own top-tier membership, known as Ultra, which commands a monthly fee of €65 for new German subscribers. By undercutting Revolut by €10 while offering a comparable mix of lifestyle perks, travel benefits, and investment tools, N26 is signaling an aggressive push to capture the most lucrative demographic of European retail banking customers.
This move mirrors a wider industry trend toward the "super-app" model, popularized across Asia and increasingly making inroads in Western markets. Financial institutions are realizing that transactional banking alone yields narrow margins, particularly in an environment of shifting interest rates. By bundling non-banking services—such as cloud storage, artificial intelligence tools, virtual private networks, and e-commerce memberships—digital banks can build sticky, high-retention customer relationships.
For N26, the success of Aura could redefine its revenue mix. While interchange fees and traditional lending have historically formed the bedrock of neobank revenues, high-margin monthly subscription models provide a predictable, recurring income stream. Furthermore, by capturing customers who use a wide array of investment and lifestyle features, N26 deepens engagement, reducing churn and increasing the lifetime value of each account holder.
Executive Perspective and Corporate Vision
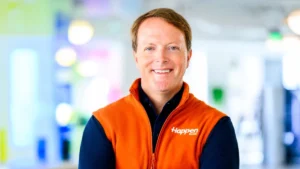
Addressing the strategic rationale behind the new top-tier account, N26 CEO and co-founder Mike Dargan emphasized the changing nature of modern consumer lifestyles.
"The launch of N26 Aura marks a major milestone in our broader strategy to further evolve N26 from a bank into a fully integrated financial platform," Dargan stated. "How our customers live, work, and express themselves is fluid, and Aura is designed to fit naturally into that modern rhythm—combining our highest tier of banking with an elevated, seamless banking experience."
Dargan’s commentary highlights a crucial pivot in how digital banks market themselves. Rather than focusing purely on low fees or zero-cost foreign exchange, contemporary neobanks are increasingly competing on identity, convenience, and ecosystem integration. Aura is explicitly tailored for individuals whose personal and professional lives require mobility, digital security, and seamless financial management across borders.
Company Background, Chronology, and Financial Turnaround
The launch of Aura arrives at a time of profound operational maturity for N26. Founded in Berlin in 2013 by Valentin Stalf and Maximilian Tayenthal, the company officially launched its mobile banking application to the public in 2015. Over the subsequent decade, N26 expanded aggressively across Europe, eventually securing a valuation north of $9 billion during a massive funding round in 2021, having raised more than €1.8 billion in total venture capital funding to date.
However, the company’s trajectory has not been without significant hurdles. Regulatory scrutiny regarding anti-money laundering controls and customer onboarding backlogs forced N26 to implement stringent growth caps imposed by Germany’s financial watchdog, BaFin, which limited its daily customer acquisition capacity for several years. In response to shifting global strategies and regulatory pressures, N26 made the strategic decision to exit the United States market in 2022, pivoting its full operational focus back toward strengthening its core European footprint.
The turnaround efforts bore significant fruit. In 2025, N26 reported a historic financial milestone: its first full year of profitability. The digital bank posted €501.6 million in annual revenue alongside a positive net income of €1.6 million. Today, N26 serves more than 5.6 million revenue-relevant customers spread across 24 European markets. Having successfully transitioned from a hyper-growth, loss-making startup into a self-sustaining financial institution, the company is now channeling its newfound operational stability into high-value product innovations like Aura.
Market Implications and Future Outlook
The rollout of N26 Aura serves as a fascinating litmus test for the European digital banking sector. For years, neobanks competed on a race-to-the-bottom pricing model, offering free or low-cost accounts to acquire massive user bases. As venture capital funding has tightened globally and profitability has become the primary metric of corporate health, digital banks have had to fundamentally rethink their monetization strategies.
By testing a €55 monthly price point, N26 is probing the upper limits of consumer price elasticity for lifestyle-integrated banking. If Aura achieves strong adoption among German professionals and businesses, it could prompt other European digital lenders to reevaluate their premium offerings, accelerating a race toward lifestyle-bundled financial products.
Nevertheless, risks remain. In an economic climate where consumers are increasingly mindful of recurring subscription fatigue, convincing a critical mass of users to pay nearly €660 annually for a bank account requires flawless execution and tangible, everyday utility. Whether the allure of a ceramic mirror-finish card, unlimited lounge access, and bundled AI and productivity subscriptions will be enough to conquer the high-end European market remains one of the most compelling narratives to watch in modern fintech.