Some Thoughts on Spending: Reevaluating the Psychology of Financial Independence in a Modern Economy

The discourse surrounding Financial Independence (FI)—a movement centered on aggressive saving and strategic investing to achieve early retirement—has recently shifted toward a critical examination of long-term consumption habits. As proponents of the FI movement reach their savings milestones, a paradoxical challenge has emerged: the inability of long-term savers to transition into a "spending" phase. This behavioral rigidity, often described as a side effect of years of disciplined frugality, has prompted experts and practitioners alike to reconsider the philosophy of wealth accumulation and its ultimate purpose.
The Evolution of the Frugality Paradigm
For decades, the standard narrative within the FI community was rooted in the concept of "delayed gratification." By prioritizing asset accumulation over immediate consumption, individuals sought to decouple their survival from traditional employment. However, recent observations by prominent financial thinkers suggest that the behaviors required to build wealth—such as extreme cost-cutting and a focus on low-cost, broad-based index funds—do not automatically dissolve upon reaching financial security.
Critics of the movement argue that this fixation on saving creates a "scarcity mindset" that persists long after the financial need for it has passed. This phenomenon, which psychologists sometimes refer to as "loss aversion" or "hedonic treadmill" in reverse, can leave individuals trapped in a state of self-imposed deprivation. The central question for the modern practitioner is no longer merely "how to save," but rather "how to effectively deploy resources to maximize utility" once one has achieved financial independence.
Data and Financial Foundations
Financial independence is mathematically defined by the "4% rule," a guideline popularized by the 1998 Trinity Study. This research suggested that a retiree could withdraw approximately 4% of their initial portfolio balance annually—adjusted for inflation—with a high probability that the assets would last for at least 30 years.
While the 4% rule provides a mechanical framework for spending, it fails to address the emotional complexity of transitioning from a saver to a spender. Data from behavioral economists indicates that high-earning savers often struggle with "wealth-related anxiety," a condition where the fear of market volatility or unexpected expenses prevents them from enjoying their capital. In contrast, historical market performance shows that consistent, long-term exposure to equities has historically outpaced inflation, creating a surplus that many FI practitioners eventually find themselves unable to spend down.
The Concept of "The Infinite Purse"
A significant shift in the FI discourse involves the "Arkadian principle," named for the fictional protagonist in George S. Clason’s 1926 classic, The Richest Man in Babylon. The principle posits that once an individual accumulates a sufficient base of income-producing assets, every subsequent expenditure is effectively "free," provided that the rate of return exceeds the rate of withdrawal.
This economic reality transforms the nature of consumption. When an individual reaches a point where their passive income (dividends, interest, and capital gains) covers their cost of living, they are no longer spending "principal" but rather the "excess" of their wealth. This shifts the internal dialogue from "can I afford this?" to "does this expenditure improve my life?" This transition is critical for moving beyond the deprivation trap.
The Declining Utility of Luxury Goods
Modern consumer behavior presents a distinct challenge to the traditional FI ethos. As technology integration increases in luxury sectors—particularly in automotive and home appliances—many consumers are expressing a preference for simplicity over complexity.
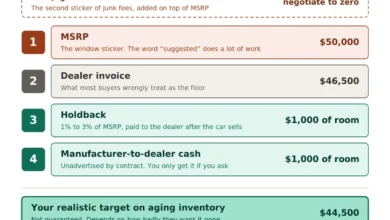
In a recent, albeit anecdotal, observation at a major dealership, participants across various age demographics demonstrated a collective rejection of "feature-heavy" luxury vehicles. The industry trend of integrating telemetry, constant connectivity, and touchscreen-dependent interfaces has created a market segment that feels alienated by modern luxury. This highlights a broader trend: as wealth increases, the marginal utility of high-tech, high-cost goods often decreases. Consequently, many high-net-worth individuals are pivoting toward "restorative" consumption—investing in the refurbishment of legacy goods or prioritizing experiences that offer tangible, personal value rather than status signaling.
Institutional and Economic Implications
The debate over spending is not limited to the individual; it mirrors larger macroeconomic discussions. The federal government’s fiscal trajectory, currently characterized by a national debt nearing $40 trillion, provides a cautionary tale regarding the relationship between spending and sustainability. With interest payments on federal debt now representing nearly 15% of total government spending, the macro-level lesson is clear: when expenditures outpace the growth of the underlying asset base, long-term stability is compromised.
For the private citizen, the implications are profound. Financial independence is not merely about the absence of work; it is about the acquisition of autonomy. When an individual reaches the "Enough" threshold, the requirement to perform labor for survival is removed, leaving a void that is often filled by productive, creative, or altruistic pursuits.
The Role of Work and Purpose
A prevailing myth in the FI movement is that the goal is the total cessation of work. In reality, modern labor data and psychological studies suggest that humans are hardwired for engagement. The dissatisfaction often associated with modern employment is rarely the work itself, but rather the lack of control over one’s time and professional environment.
When the financial pressure of the "paycheck-to-paycheck" cycle is removed, individuals frequently migrate toward work that provides intrinsic rather than extrinsic reward. This includes mentorship, craftsmanship, writing, or philanthropy. The "Give Like a Billionaire" philosophy, which encourages individuals to distribute their surplus wealth, is gaining traction as a final stage of financial maturity. By transitioning from accumulation to distribution, the individual finds a renewed sense of purpose that transcends the acquisition of goods.
Future Outlook and Conclusion
The transition from a "saver" to a "spender" is a complex psychological journey. It requires a fundamental reassessment of the purpose of money. While the initial phase of the journey is defined by the rigid discipline of wealth creation, the final phase must be defined by the intentionality of wealth deployment.
As the FI community matures, it is likely that the focus will move further away from "retiring" and toward "optimizing." This involves:
- Defining "Enough": Using quantitative data to determine the floor of financial security.
- Valuing Utility over Status: Distinguishing between goods that offer genuine life improvement and those that merely serve as depreciating assets.
- Embracing Autonomy: Using financial independence as a platform for meaningful, self-directed work rather than passive consumption.
Ultimately, the goal of achieving financial independence is not to stop living, but to start living with the agency that only capital can provide. Whether one chooses to continue building wealth or to begin distributing it, the freedom to choose is the final, most valuable asset of all. As the global economy continues to evolve, the ability to balance fiscal prudence with the pursuit of a well-lived life remains the defining challenge of the modern era.