quantitative
-
Automated Trading and Algorithmic Strategies
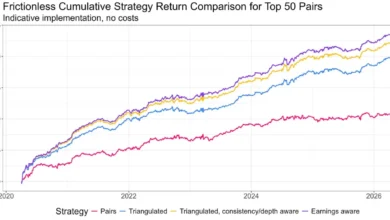
Part 6 of 6 Statistical Arbitrage for Independent Traders: A Comprehensive Analysis of Triangulated Strategies and Modern Quantitative Infrastructure
The landscape of quantitative trading for independent operators has undergone a profound structural shift over the past decade. Historically, statistical…
Read More » -
Automated Trading and Algorithmic Strategies
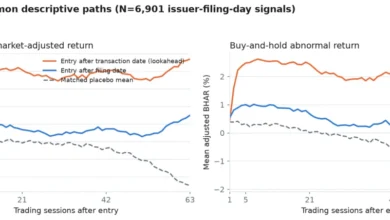
Quantitative Analysis of SEC Form 4 Insider Purchase Filings Reveals Short Term Market Associations and Statistical Nuance
The United States Securities and Exchange Commission (SEC) maintains a vast, publicly accessible repository of financial disclosures that serves as…
Read More » -
Automated Trading and Algorithmic Strategies
The Foundational Architecture of Systematic Trading: Why Data Infrastructure Dictates Quantitative Success
Algorithmic trading systems are frequently glamorized through the lens of sophisticated machine learning models, complex signal generation, and high-frequency execution…
Read More » -
Automated Trading and Algorithmic Strategies
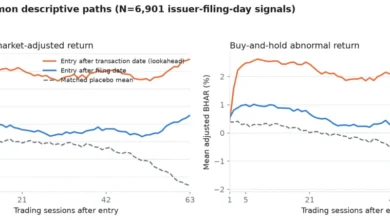
Quantitative Analysis of Insider Purchase Filings: Evaluating Market Response and Informational Value
The U.S. Securities and Exchange Commission’s Form 4 filings have long served as a cornerstone for quantitative researchers seeking to…
Read More » -
Automated Trading and Algorithmic Strategies
The Illusory Edge: How Artificial Intelligence is Flooding Retail Quantitative Trading with False Discoveries
The democratization of financial technology has historically been heralded as a triumph for retail investors, lowering barriers that once kept…
Read More » -
Automated Trading and Algorithmic Strategies
Why Large Language Models Fail at Quantitative Trading Research: A Structural Analysis
The intersection of artificial intelligence and financial market research has sparked widespread debate across the global quantitative trading community, fueled…
Read More » -
Automated Trading and Algorithmic Strategies
Beyond the Ticker: How Quantitative Analysts Separate Market Edge from Statistical Noise
The modern financial landscape is awash in algorithmic trading strategies, with quantitative funds and independent investors perpetually searching for systemic…
Read More » -
Automated Trading and Algorithmic Strategies
Mastering Asset Allocation Through Risk Parity: A Quantitative Approach to Portfolio Stability
Most investors focus their energy on the art of stock picking, yet academic research and institutional data consistently confirm that…
Read More » -
Automated Trading and Algorithmic Strategies
The Illusion of Optimization: Why Data Mining and Vibe Quanting Fail in Modern Quantitative Finance
The rapid evolution of retail quantitative finance over the past decade has given rise to two distinct yet philosophically identical…
Read More » -
Automated Trading and Algorithmic Strategies
Mastering Quantitative Breakout Strategies: A Technical Analysis of Donchian Channels and Algorithmic Implementation
The evolution of financial markets has shifted the focus of individual and institutional traders toward systematic, rule-based methodologies that remove…
Read More »
